The money that leaves you every April could be building the wall instead. One plan, two countries: a smaller tax bill this year, and what’s left of it sitting somewhere a lawsuit has to start over from zero. You already did the hard part. This is about getting to keep it.
 Trish WilsonU.S. NAR Realtor · PRC-licensed PH broker · U.S. life insurance licensed · mortgages in both countries
You already know it. It’s why you formed the entity, bought the umbrella, and told yourself you were covered.
Thirty years. Every weekend. Every payroll you made in a month you didn’t pay yourself.
It can be gone on a filing you never saw coming. Not because you did anything wrong. Because somebody decided to come at you — a customer, a competitor, an employee, an accident, an ex-spouse’s lawyer who smells a balance sheet.
And every April you hand over a number that still makes you go quiet for a minute. For the privilege of carrying all of that risk yourself.
Here’s the thing. You did everything you were told to do. The entity. The umbrella. The CPA you’ve trusted for fifteen years. None of it was wrong.
It’s just all in the same country. One court system. One afternoon’s work for somebody with a grievance and a lawyer. Nobody ever told you that’s a position, not a plan.
What if the money that leaves you every April built the second wall instead?
Your business funds a pension plan under IRC §412(e)(3), built on guaranteed life insurance contracts. The contribution is deductible this year. For a profitable owner past 45 with few employees, that is six figures off this April.
Then the money sits somewhere unusual. In Patterson v. Shumate, 504 U.S. 753 (1992), the U.S. Supreme Court held that assets inside a qualified ERISA plan are protected from creditors. Not clever drafting. The highest court in your country.
So the same dollar does two jobs: it leaves your tax bill, and it lands somewhere a lawsuit can’t follow it.
Two things said plainly, because you’d ask. It’s a deferral — you pay tax when you draw it, presumably at a lower rate. And yes, this is life insurance, and Trish earns a commission on it. The tax code requires insurance contracts to fund this kind of plan. That’s the statute, not a sales preference.
What did you write that cheque for last April?
A U.S. judgment isn’t worth the paper it’s printed on in Manila. Under Rule 39, Section 48, no Philippine sheriff acts on it. Your creditor has to hire Filipino lawyers, file a brand-new case asking a Philippine court to recognise it, and beat you twice. Most of them look at that and stop.
That isn’t a loophole someone found. In Mijares v. Rañada, G.R. No. 139325 (2005), the Philippine Supreme Court set out the rule directly: a foreign judgment is evidence of a right, not an order a Philippine court will execute. The creditor starts a fresh case here, and has to win it. Their highest court, saying so, the same way yours did.
And your title there is solid, which is the part Americans get wrong. The Philippines runs the Torrens system — installed in 1902, under American administration. You get a certificate of title and a searchable government register, doing the same job your county recorder and your abstract of title do at home. You look the property up, you see who owns it and what is against it, and then your name goes on it. The difference is in your favour: the register is the title, issued by the state and backed by it.
Same rulebook. Different courthouse. That’s the whole reason this works, and it’s why it’s the Philippines and not two hundred other countries.
How much of what you own could be reached by one filing, this afternoon?
Their dry season runs November to February. It lands exactly on your winter — the best months there, the worst ones where you are.
Private hospitals in Manila and Cebu carry JCI accreditation, the same international standard used for U.S. hospitals, at a fraction of the price. English runs the courts, the contracts and the business, so nothing gets translated for you. And the SRRV retirement visa gives indefinite residency when the months turn into something longer.
You’ve been to Mexico. You’ve been to Italy. Neither one puts your name on a government-guaranteed title.
What would you do with the first February you didn’t have to be cold for?
A foreign national owns a condominium unit outright, titled in his own name. Former natural-born Filipinos and dual citizens can own land. Land can also be held through a properly capitalised Philippine corporation. Pick who you are.
Whichever route fits you, the finish is the same: a certificate of title in the national register with your name on it.
Which of those three are you?
Walk into a Philippine bank cold as a foreign national and you’ll probably get a no. That one bad experience is why half the internet tells you this is a cash-only market. It isn’t.
| Walking in yourself | Through our desk | |
|---|---|---|
| Loan-to-value | Commonly 50–70%, when offered | 70–80% |
| Rate | Retail foreign-national pricing | U.S.-competitive |
| Term | Often shortened for non-residents | 15 to 30 years |
| Who presents your file | You do | We do |
Trish writes mortgages in both countries, so U.S. money and Philippine money get compared in one conversation instead of three. Two other routes are often cheaper and we’ll say so when they are: developer in-house financing on a presale, or simply using U.S.-side liquidity.
Would you rather tie up cash, or keep it working?
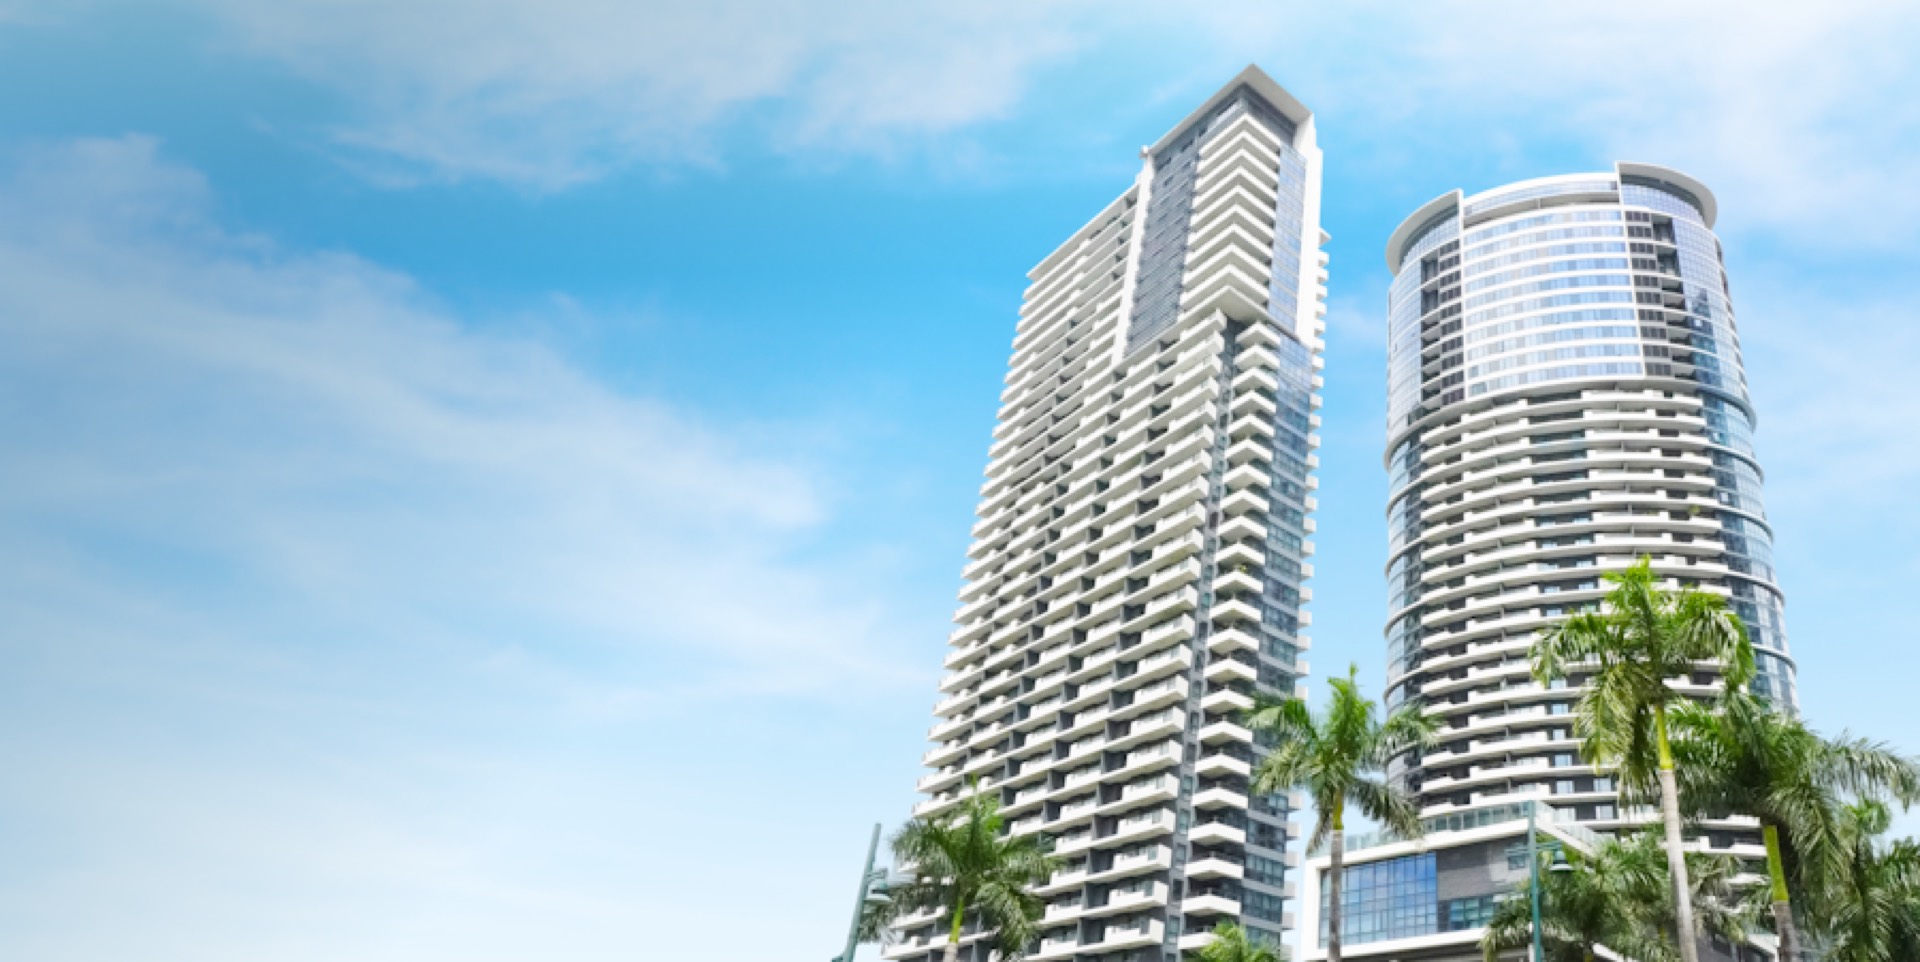
Four of the developer projects we broker. Behind them we currently hold over ₱5 billion — roughly US$80 million — in condominium units and private-party Philippine houses listed with us, across developers and individual sellers.
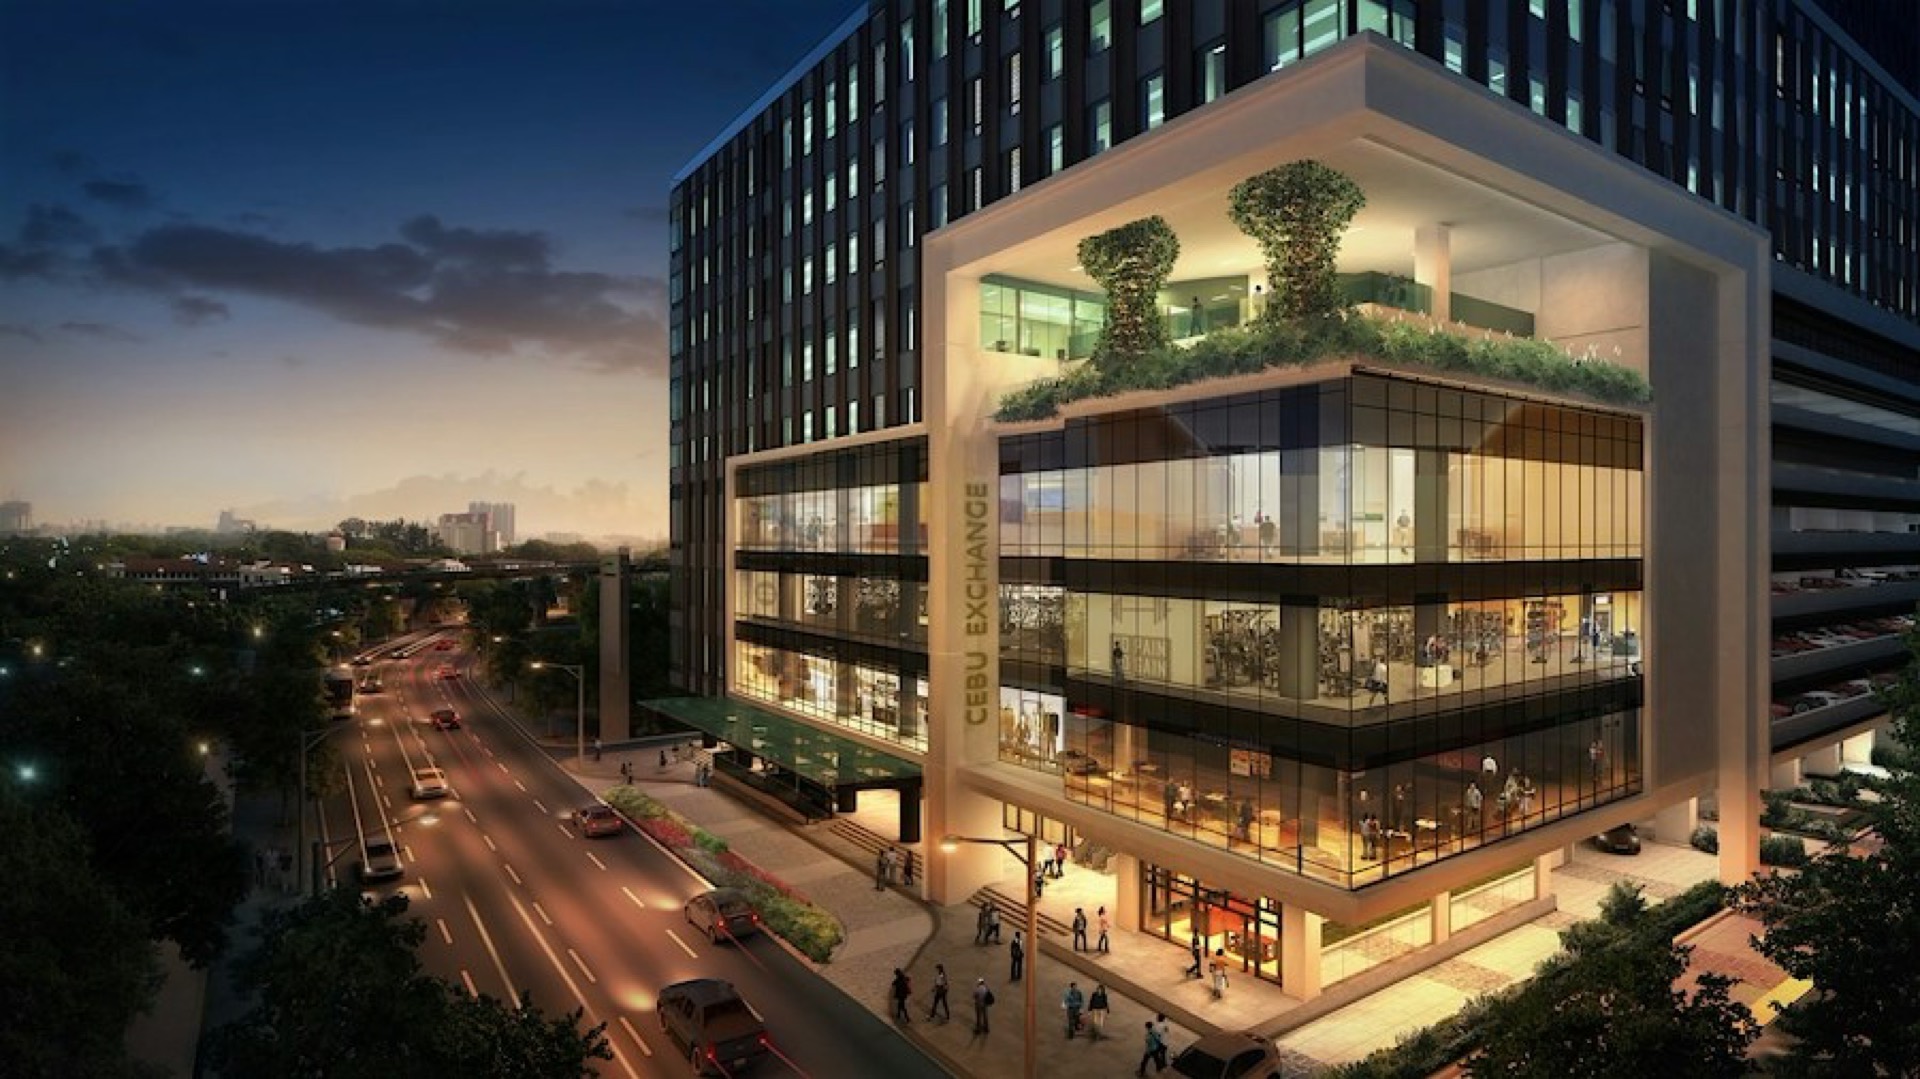
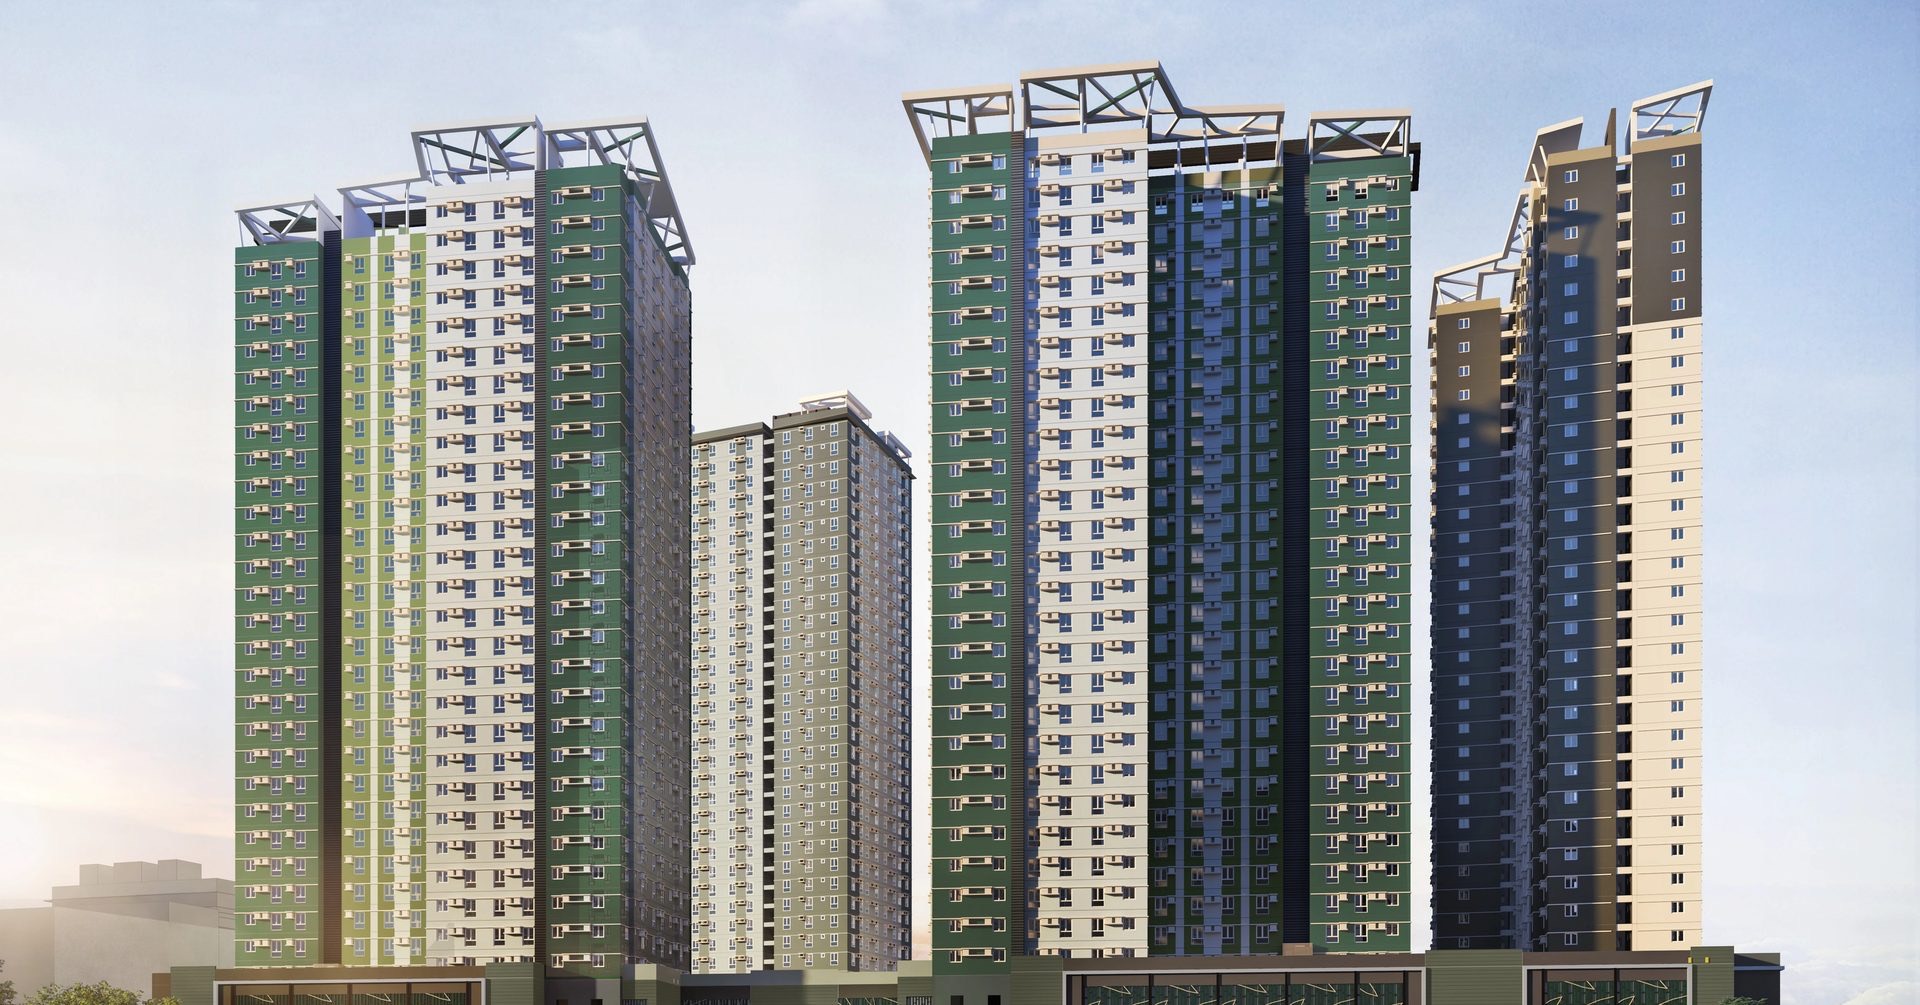
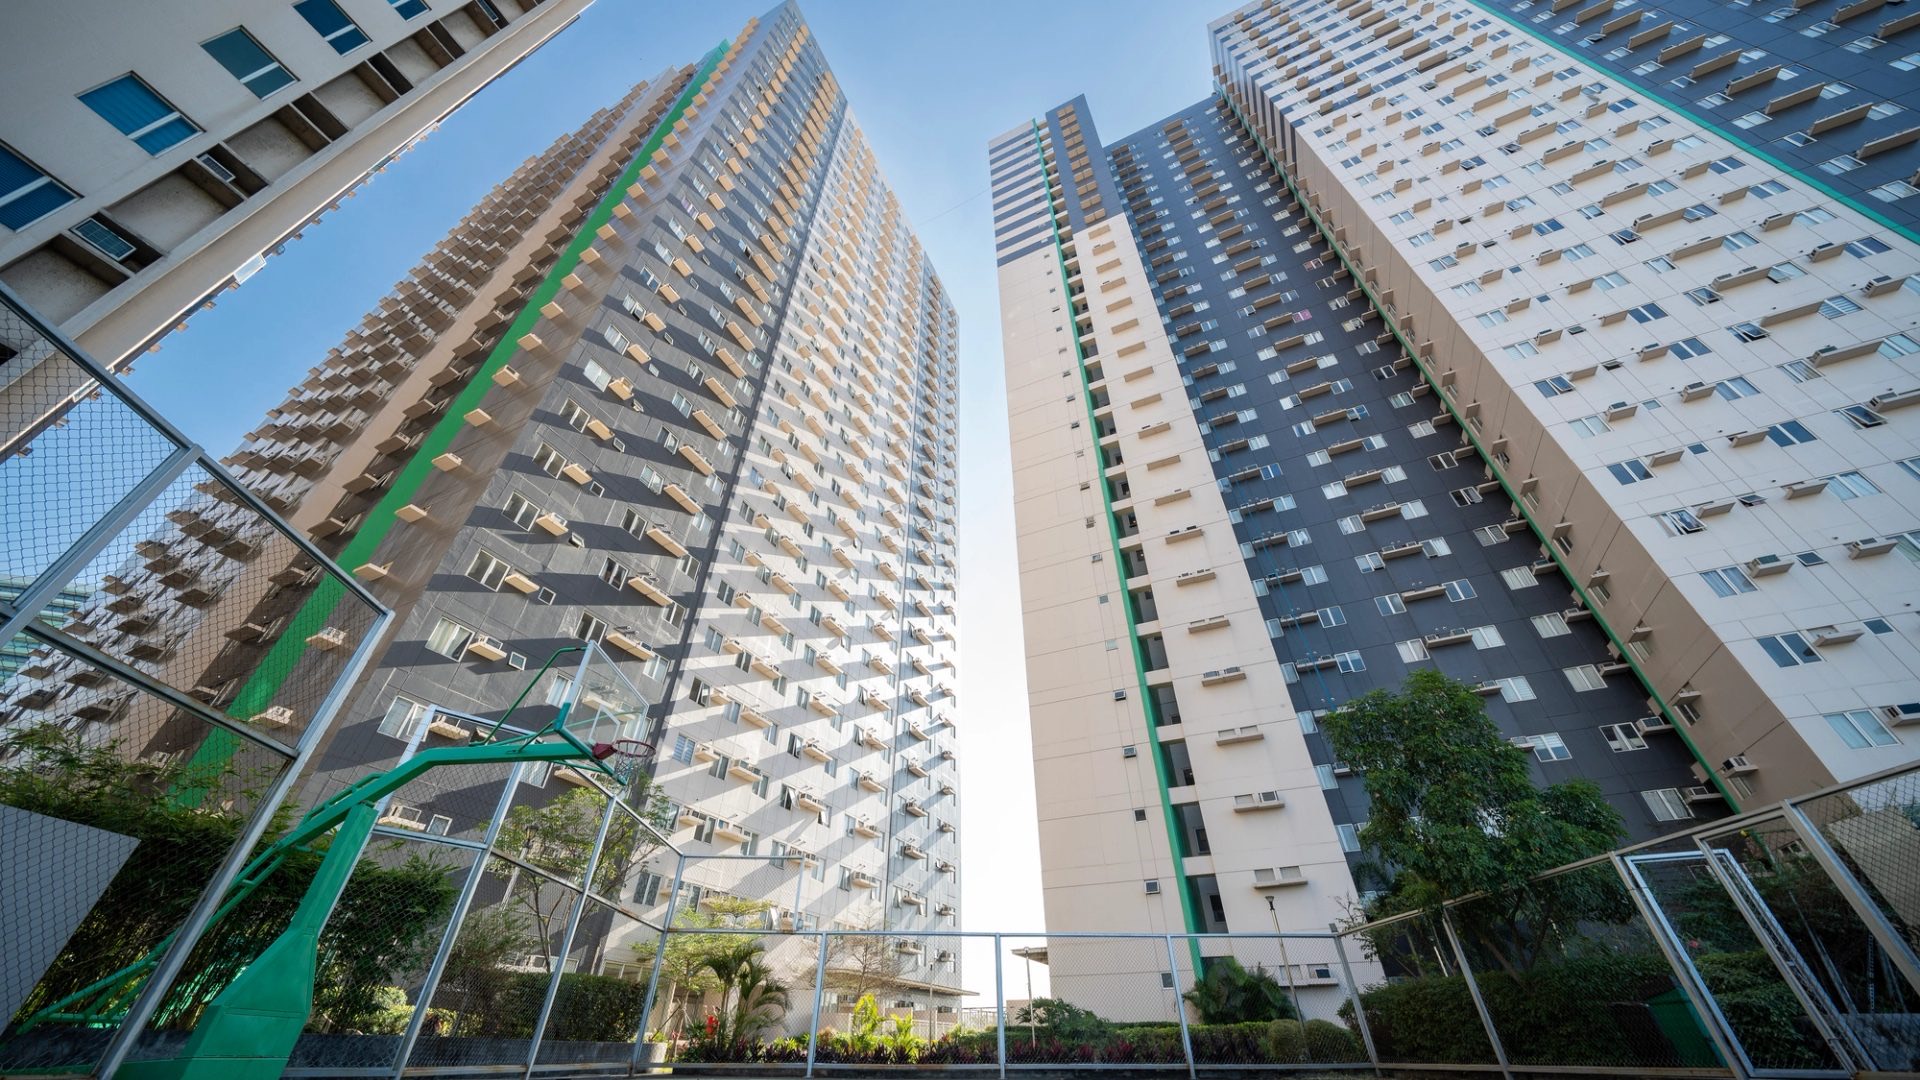
See everything we have listed →
globalrealtor4acause.com · developer inventory and private-party listings, updated continuously.
Financing. Investing. Tax. Estate. Retirement. Diversification across two countries. Asset protection. Normally that’s five professionals who have never met each other, and you in the middle translating.
Trish Wilson is a U.S. NAR Realtor, a PRC-licensed Philippine real estate broker, U.S. life insurance licensed, and writes mortgages in both countries. She’s a degreed accountant and a former licensed CPA, U.S.-trained as a tax preparer through H&R Block. She has done tax planning and prepared corporate and personal returns, and she has run corporations in the United States and the Philippines.
But that’s the whole problem she solves. Everyone else can answer one fifth of your question.
What would you ask first, if you could ask all of it in one conversation?