
Short answer: yes, as of 2026, for a condominium unit. A year ago the honest answer was “almost never”. Selected Philippine banks now lend to foreign nationals for condominium purchases under specific conditions, and our broker, a licensed mortgage agent, arranges those loans directly. Land and house-and-lot financing remains for Filipino citizens and dual citizens. Here is what the lenders ask for, what they will not do, and how the money actually moves.
What changed
Philippine banks have always been able to lend to foreigners in principle; in practice most declined because the collateral had to be a condominium, the borrower’s income was abroad, and the bank had no way to pursue a defaulting borrower overseas. Three things shifted: lenders built overseas-income underwriting for the OFW market and extended it; condominium developers in Cebu, BGC and Makati now sell a meaningful share of units to foreign nationals; and brokers with lender relationships can present a complete, verifiable file. The programmes are selective and the terms are set per lender, which is why we do not publish a rate here.
Who the banks will lend to
| Borrower | Property the bank will finance | Typical conditions |
|---|---|---|
| Filipino citizen or dual citizen living abroad | Condo, house and lot, lot, construction | Overseas Filipino home loan programme; income documents from abroad; SPA for a Philippine signatory in some regions |
| Former Filipino (no RA 9225) | Condo; land within BP 185 limits | Same as above |
| Foreign national | Condominium unit only | Larger down payment (commonly 20% to 30%), shorter term, proof of stable income, often a long-term visa or a Filipino co-borrower; some lenders prefer the foreign spouse of a Filipino |
Minimum income thresholds and debt-service ratios apply: one major bank, for example, requires at least PHP 40,000 gross monthly income and caps debt service at 40% of income. Maximum age at loan maturity is usually 65 to 70. Philippine banks do not pull your U.S. or other foreign credit report; they require a police or NBI clearance and no bankruptcy in the last two years, plus proof of income. A few of these banks keep offices in the United States, which is one reason Americans and a few other nationalities can now be served.
What the file contains
Country-specific lists, including spouse co-borrower and special-power-of-attorney rules, are on our pages for the USA and Guam, Canada, UK, Middle East, Hong Kong, Japan and Singapore. In general:
- Passport and visa; for foreigners, proof of residence status or the Filipino co-borrower’s documents.
- Police clearance from your home country or NBI clearance, and a declaration of no bankruptcy in the last two years.
- Income: certificate of employment and payslips, or audited financial statements and bank statements if self-employed; tax returns; proof of remittances for overseas Filipinos.
- The contract to sell or reservation agreement for the unit.
- For condominium units, the developer’s licence to sell and the master deed; the bank checks the project’s foreign ownership share for a foreign borrower.
- Insurance: fire insurance on the unit, and mortgage redemption insurance where the lender requires it.
Developer financing versus bank financing
During pre-selling, the developer’s own instalment plan is open to everyone, foreign or not, usually with little or no interest while the building rises. At turnover the balance falls due, and that is where the bank loan comes in. Many foreign buyers combine the two: developer plan for the down payment over construction, bank loan for the balance. We check the turnover date against the lender’s approval window so you are not caught between the two.
Where HighTech Mortgage fits, and where it does not
Our U.S. partner HighTech Mortgage (California DRE Broker License 01106294, NMLS 291547, offices in Sacramento and Manila) is a U.S. lender: it provides mortgages on U.S. property for U.S. borrowers. It does not lend on Philippine property. Its role in a Philippine purchase is the money leg: a U.S. escrow for the transaction paperwork and payment, including digital-currency transfer of the purchase funds, with smart-contract and loan-servicing capabilities for both countries on its roadmap. Some U.S. buyers raise their Philippine down payment against U.S. equity through HighTech Mortgage and then borrow the balance from a Philippine bank; that is two loans in two countries, planned together.
A worked example
| Item | Example |
|---|---|
| Buyer | U.S. citizen, 54, married to a Filipino citizen, income $9,000 a month |
| Unit | Two-bedroom condominium, Cebu IT Park, PHP 9,000,000, within the project’s foreign share |
| Structure | 30% down (PHP 2,700,000); Philippine bank loan of PHP 6,300,000 over 15 years with the Filipino spouse as co-borrower |
| Illustrative payment | About PHP 58,000 a month at 7.5%, before association dues; rates are fixed for a chosen period then repriced |
| Money movement | Down payment through the U.S. escrow with HighTech Mortgage; loan proceeds paid by the bank to the developer |
Condominiums you can finance
Verified condominium listings and developer projects follow. Projects are shown for discovery; availability and the foreign share are confirmed at inquiry.
13 individually available listing(s) matched. 24 developer project(s) shown for discovery — a developer project is NOT an available unit. No source supplies unit-level availability, so the available-unit count is unknown rather than zero.
Available properties
 ListingAyala Condo studio fully furnished for sale in MuntinlupaMetro Manila, AlabangPHP 3,000,0001 bed · 1 bath · 22.4 m²
 Listing19.5 sqm Studio Condo for Sale — RLC Gateway Regency, Mandaluyong (Move-In Ready)Metro Manila, MandaluyongPHP 3,800,0001 bed · 1 bath · 19.5 m²
 ListingBerkley Residences Condominium Unit For Sale Katipunan/QCQuezon City (QC), Metro Manila, Quezon CityPHP 3,900,0001 bed · 2 bath · 24.4 m²
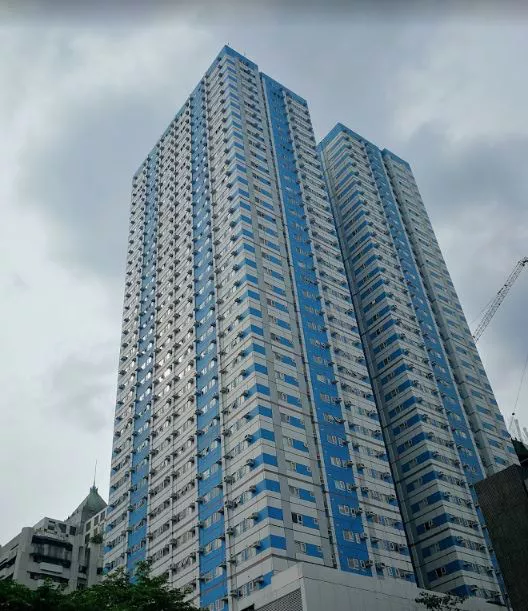 Listing24 sqm Studio Condo at The Pearl Place, Pasig — Near University of Asia & the PacificPasig, Metro Manila, PasigPHP 4,440,0001 bed · 1 bath · 24 m²
 ListingCondo for Sale at Solemare Parksuites, ParañaqueParanaque, Metro Manila, ParanaquePHP 4,950,0001 bed · 1 bath · 28 m²
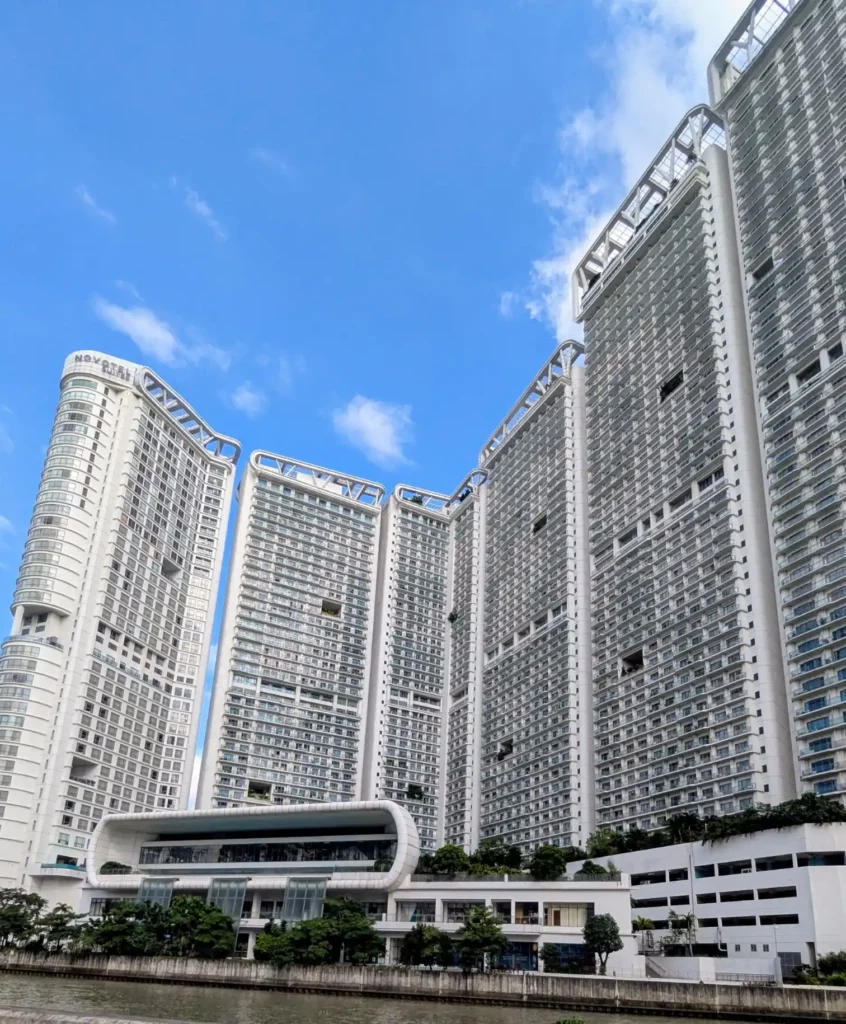 ListingAcqua-Skyline & River View Condo – MandaluyongMandaluyong, Metro ManilaPHP 5,000,0001 bed · 1 bath · 24.8 m²
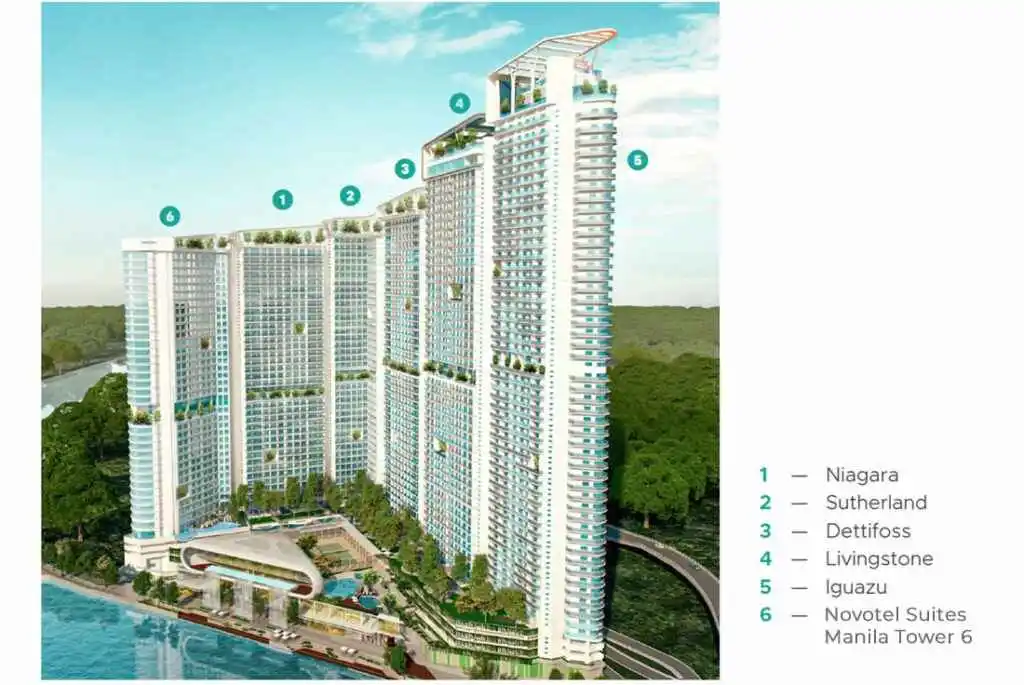 ListingAqua Residences Penthouse Condo for Sale — 1 Bedroom, Mandaluyong (Move-In Ready)Mandaluyong, Metro ManilaPHP 5,000,0001 bed · 1 bath · 24.8 m²
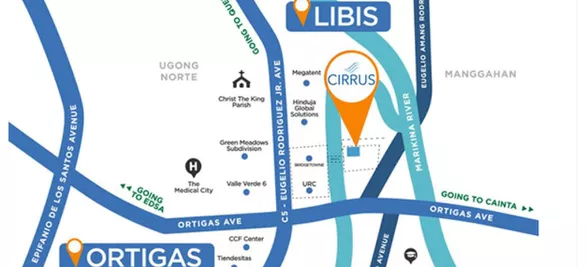 ListingStudio Condo Cirrus Bridgetowne East RLC, Pasig 24smNasugbu, Metro Manila, PasigPHP 5,500,0001 bath · 24 m²
- Listing2-Bedroom Corner Unit Condo for Sale — Ohana Place, Las Piñas (Ground Floor)Las Piñas, Metro ManilaPHP 5,800,0002 bed · 1 bath · 77 m²
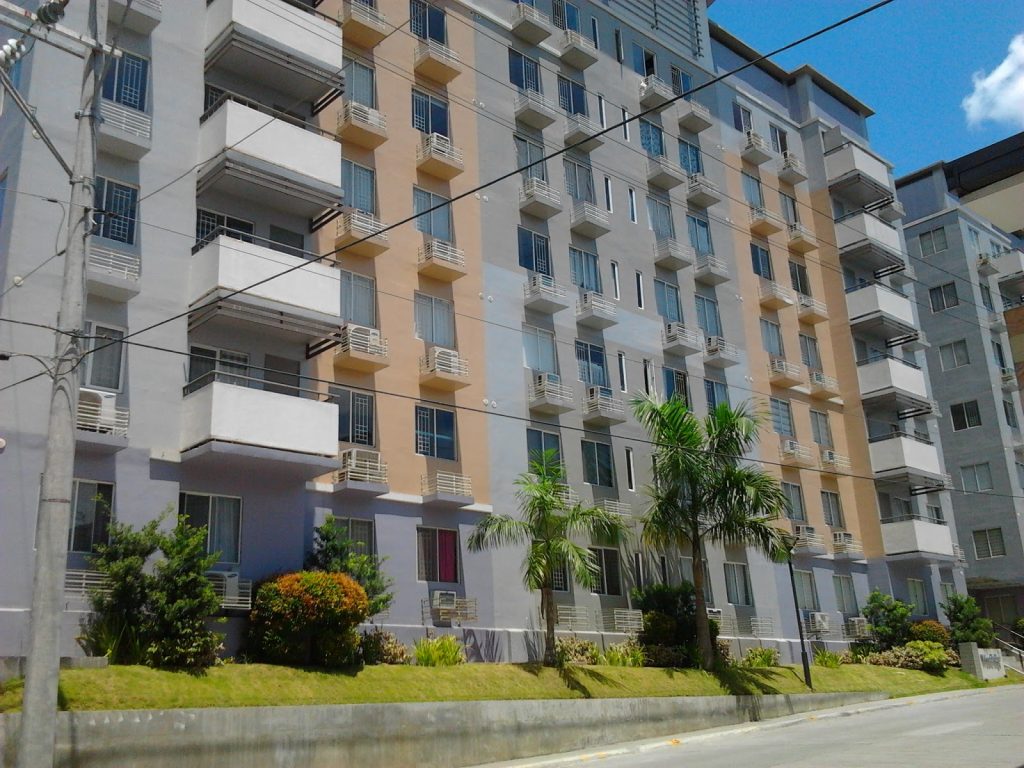 Listing2-Bedroom Condo with Parking for Sale — Sofia Bellevue, Quezon City (Ground Floor)Quezon City (QC), Metro Manila, Quezon CityPHP 7,000,0002 bed · 1 bath · 36 m²
 Listing1-Bedroom Condo for Sale — Avida Serin West Tower 2, TagaytayTagaytay, Cavite, TagaytayPHP 9,000,0001 bed · 2 bath · 41 m²
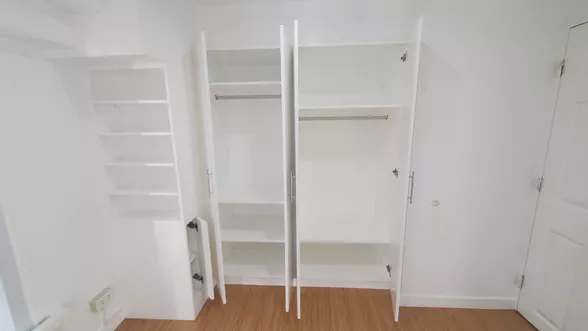 Listing2 Storey Apartment style condo @ Fort Victoria C, BGCBonifacio Global City, Metro Manila, TaguigPHP 14,350,0002 bed · 1 bath · 45 m²
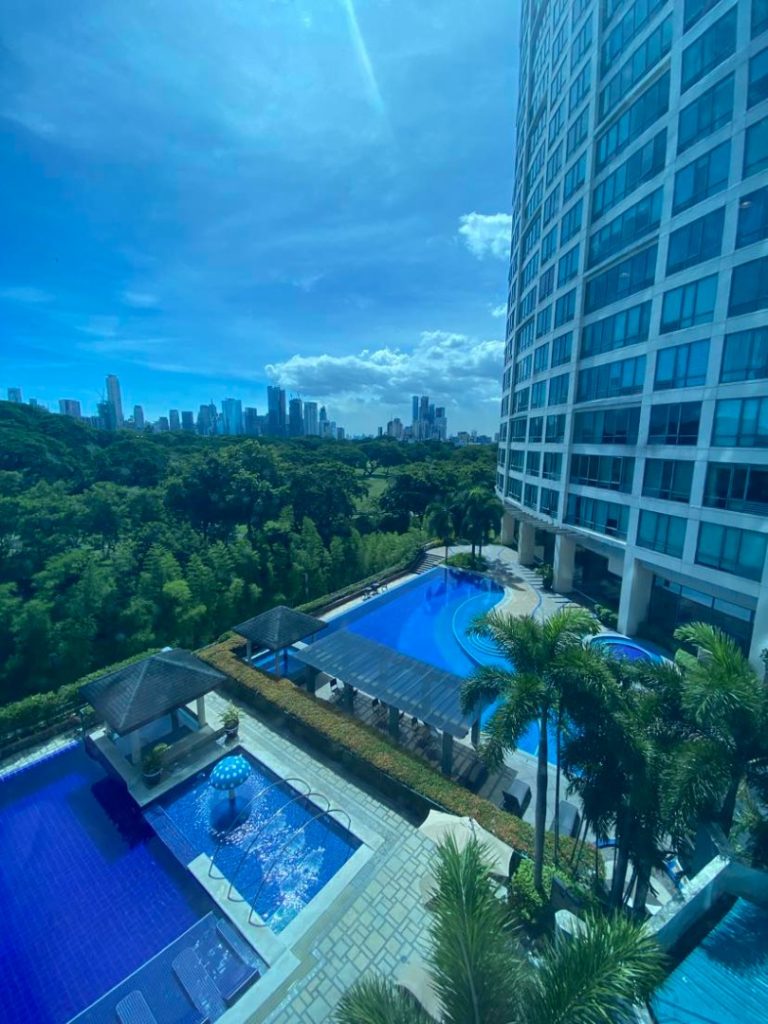 ListingBellagio 2 Condo for Sale — 2 Bedrooms with Parking, BGC TaguigBonifacio Global City, Metro Manila, BGCPHP 25,000,0002 bed · 2 bath · 86 m²
Developer projects (not individual units)
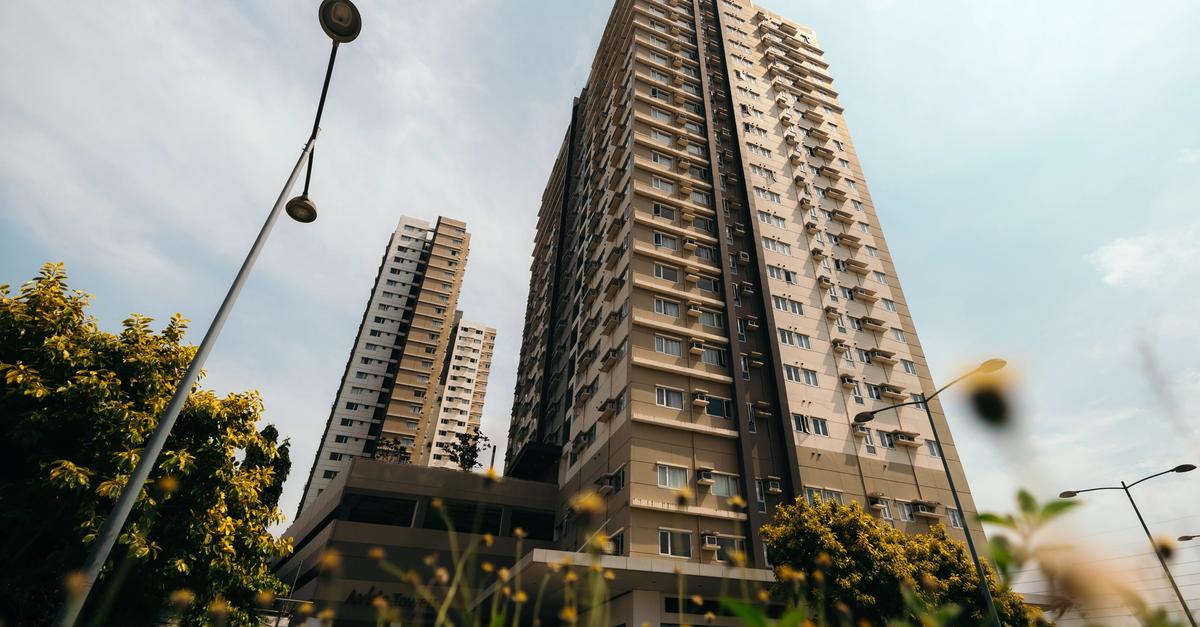 Developer projectAvida Towers AlturaMuntinlupaFrom PHP 3,980,000Ayala Land
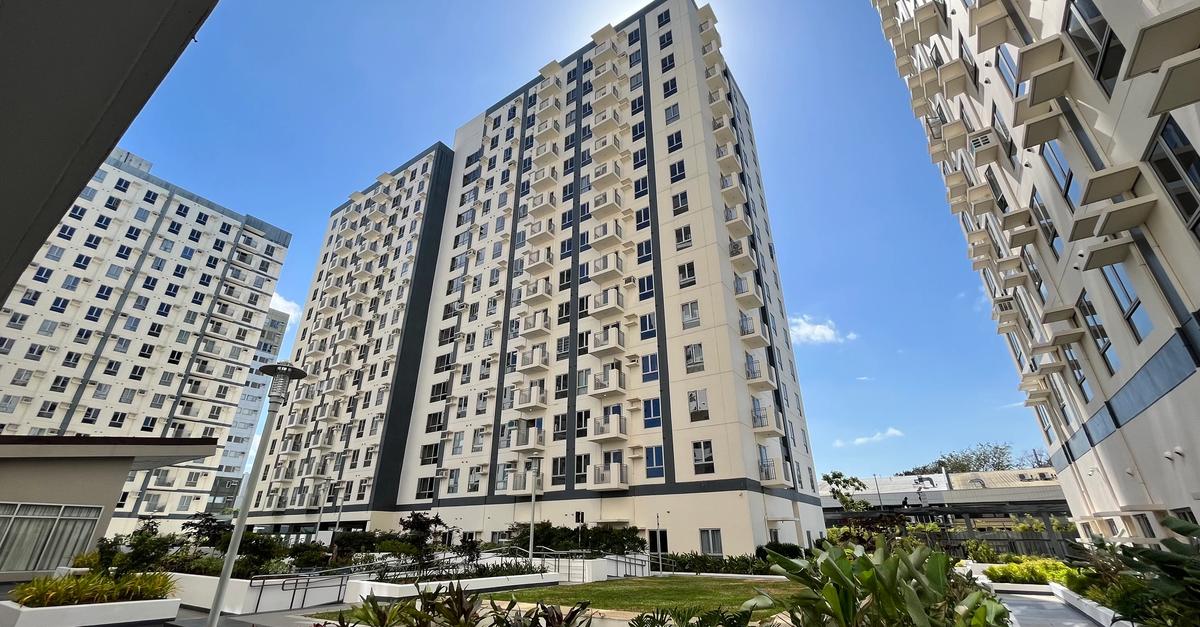 Developer projectAvida Towers VireoTaguig CityFrom PHP 5,300,000Ayala Land
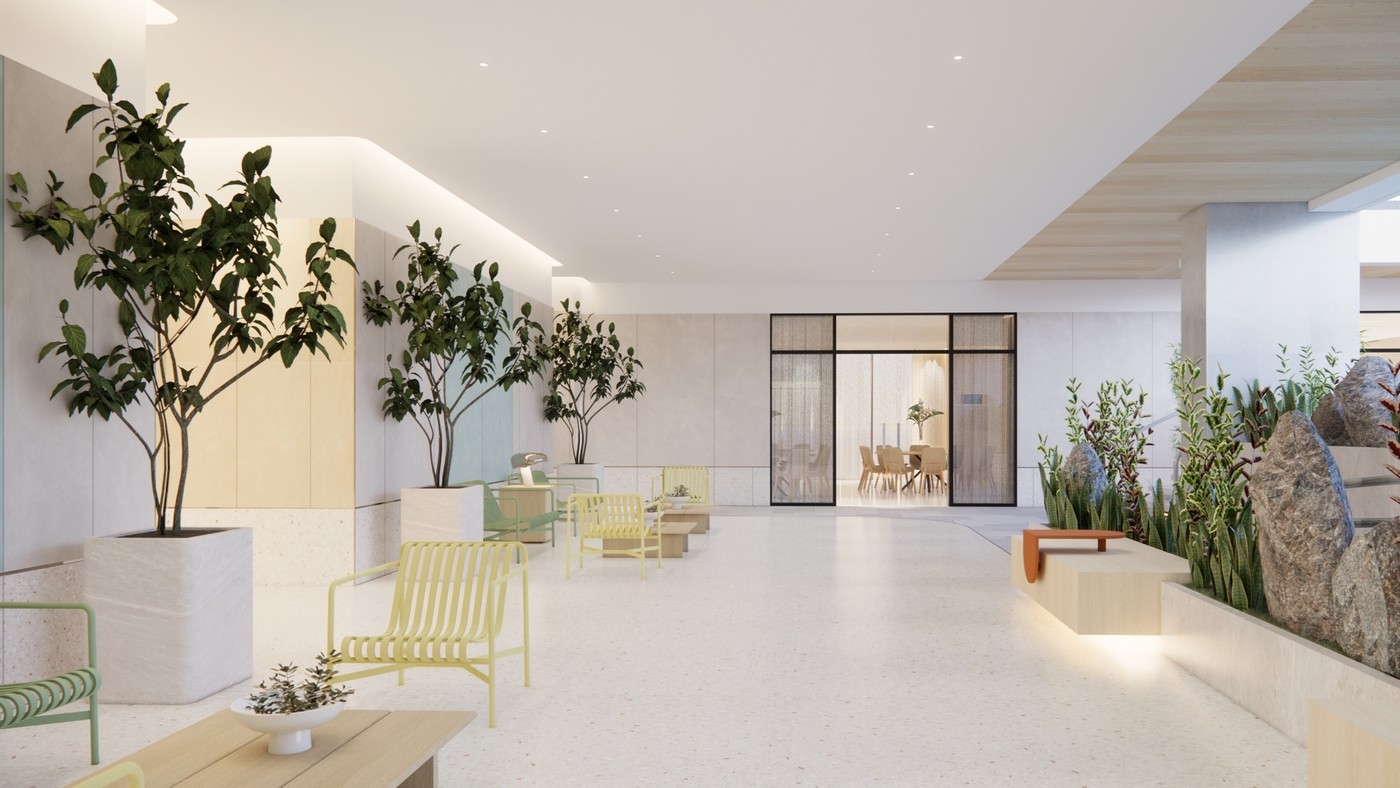 Developer projectThe Heights KatipunanKatipunan Avenue, Quezon CityFrom PHP 6,600,000Ayala Land · 3 unit types
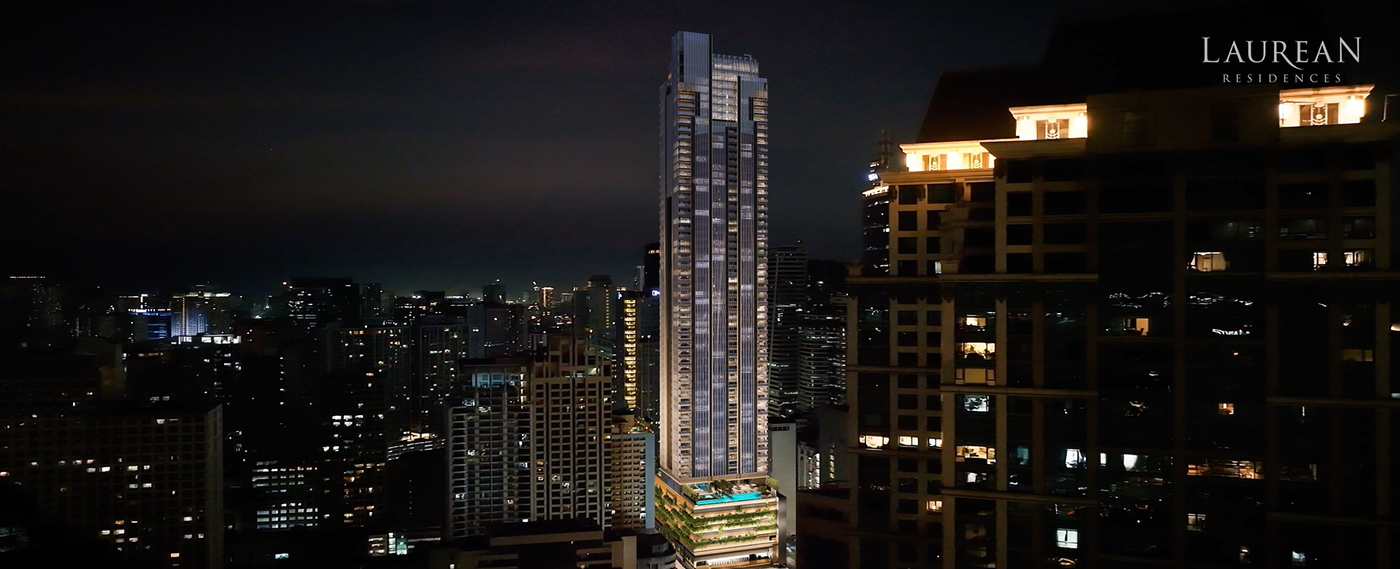 Developer projectLaureanMakati City, Metro ManilaFrom PHP 35,800,000Ayala Land
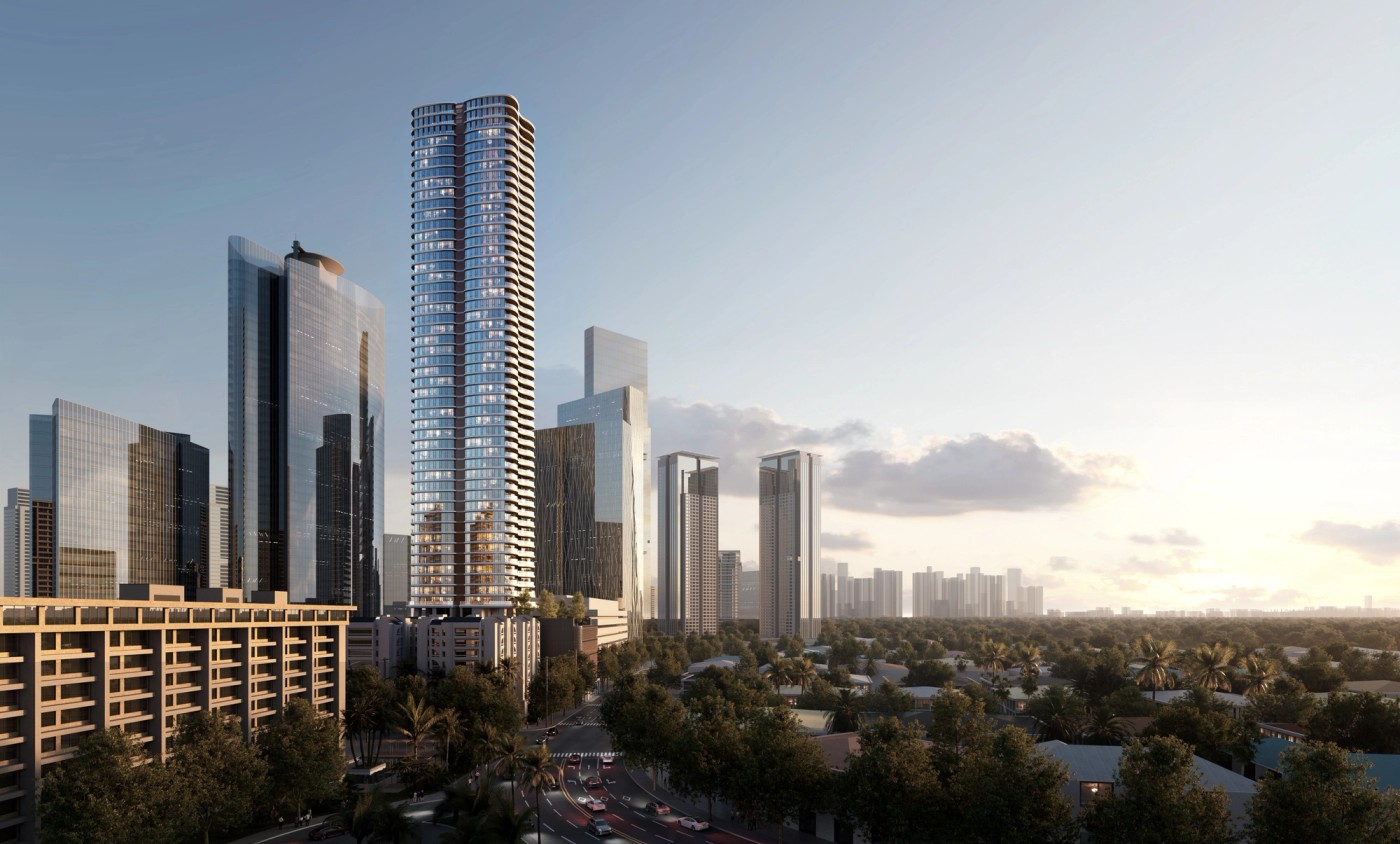 Developer projectPark VillasMakati City, Metro ManilaFrom PHP 516,000,000Ayala Land · 1 unit types
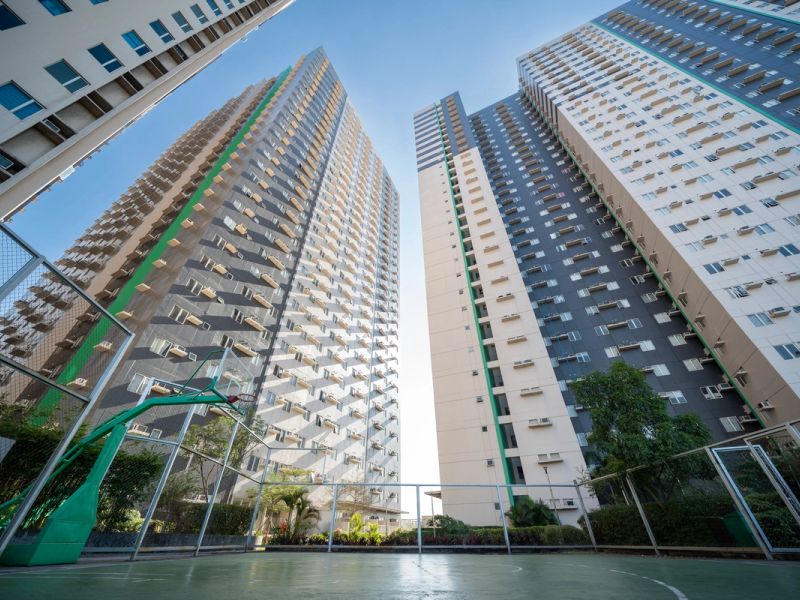 Developer projectAmaia Skies CubaoCubao, Quezon CityPrice not publishedAyala Land
 Developer projectArbor LanesTaguig, Metro ManilaPrice not publishedAyala Land
 Developer projectArya ResidencesBonifacio Global City (BGC), Taguig CityPrice not publishedArthaland
 Developer projectAvida Towers AtriaIloilo CityPrice not publishedAyala Land
 Developer projectAvida Towers RialaCebu IT Park, Cebu CityPrice not publishedAyala Land
Developer projectCentralis TowersLipa, BatangasPrice not publishedAyala Land
 Developer projectEluriaLegazpi Village, Makati CityPrice not publishedArthaland
 Developer projectGarden Court ResidencesTaguig, Metro ManilaPrice not publishedAyala Land
 Developer projectLivKatipunan, Quezon CityPrice not publishedArthaland
 Developer projectLucimaCebu Business Park, Cebu CityPrice not publishedArthaland
 Developer projectMergent ResidencesMakati, Metro ManilaPrice not publishedAyala Land
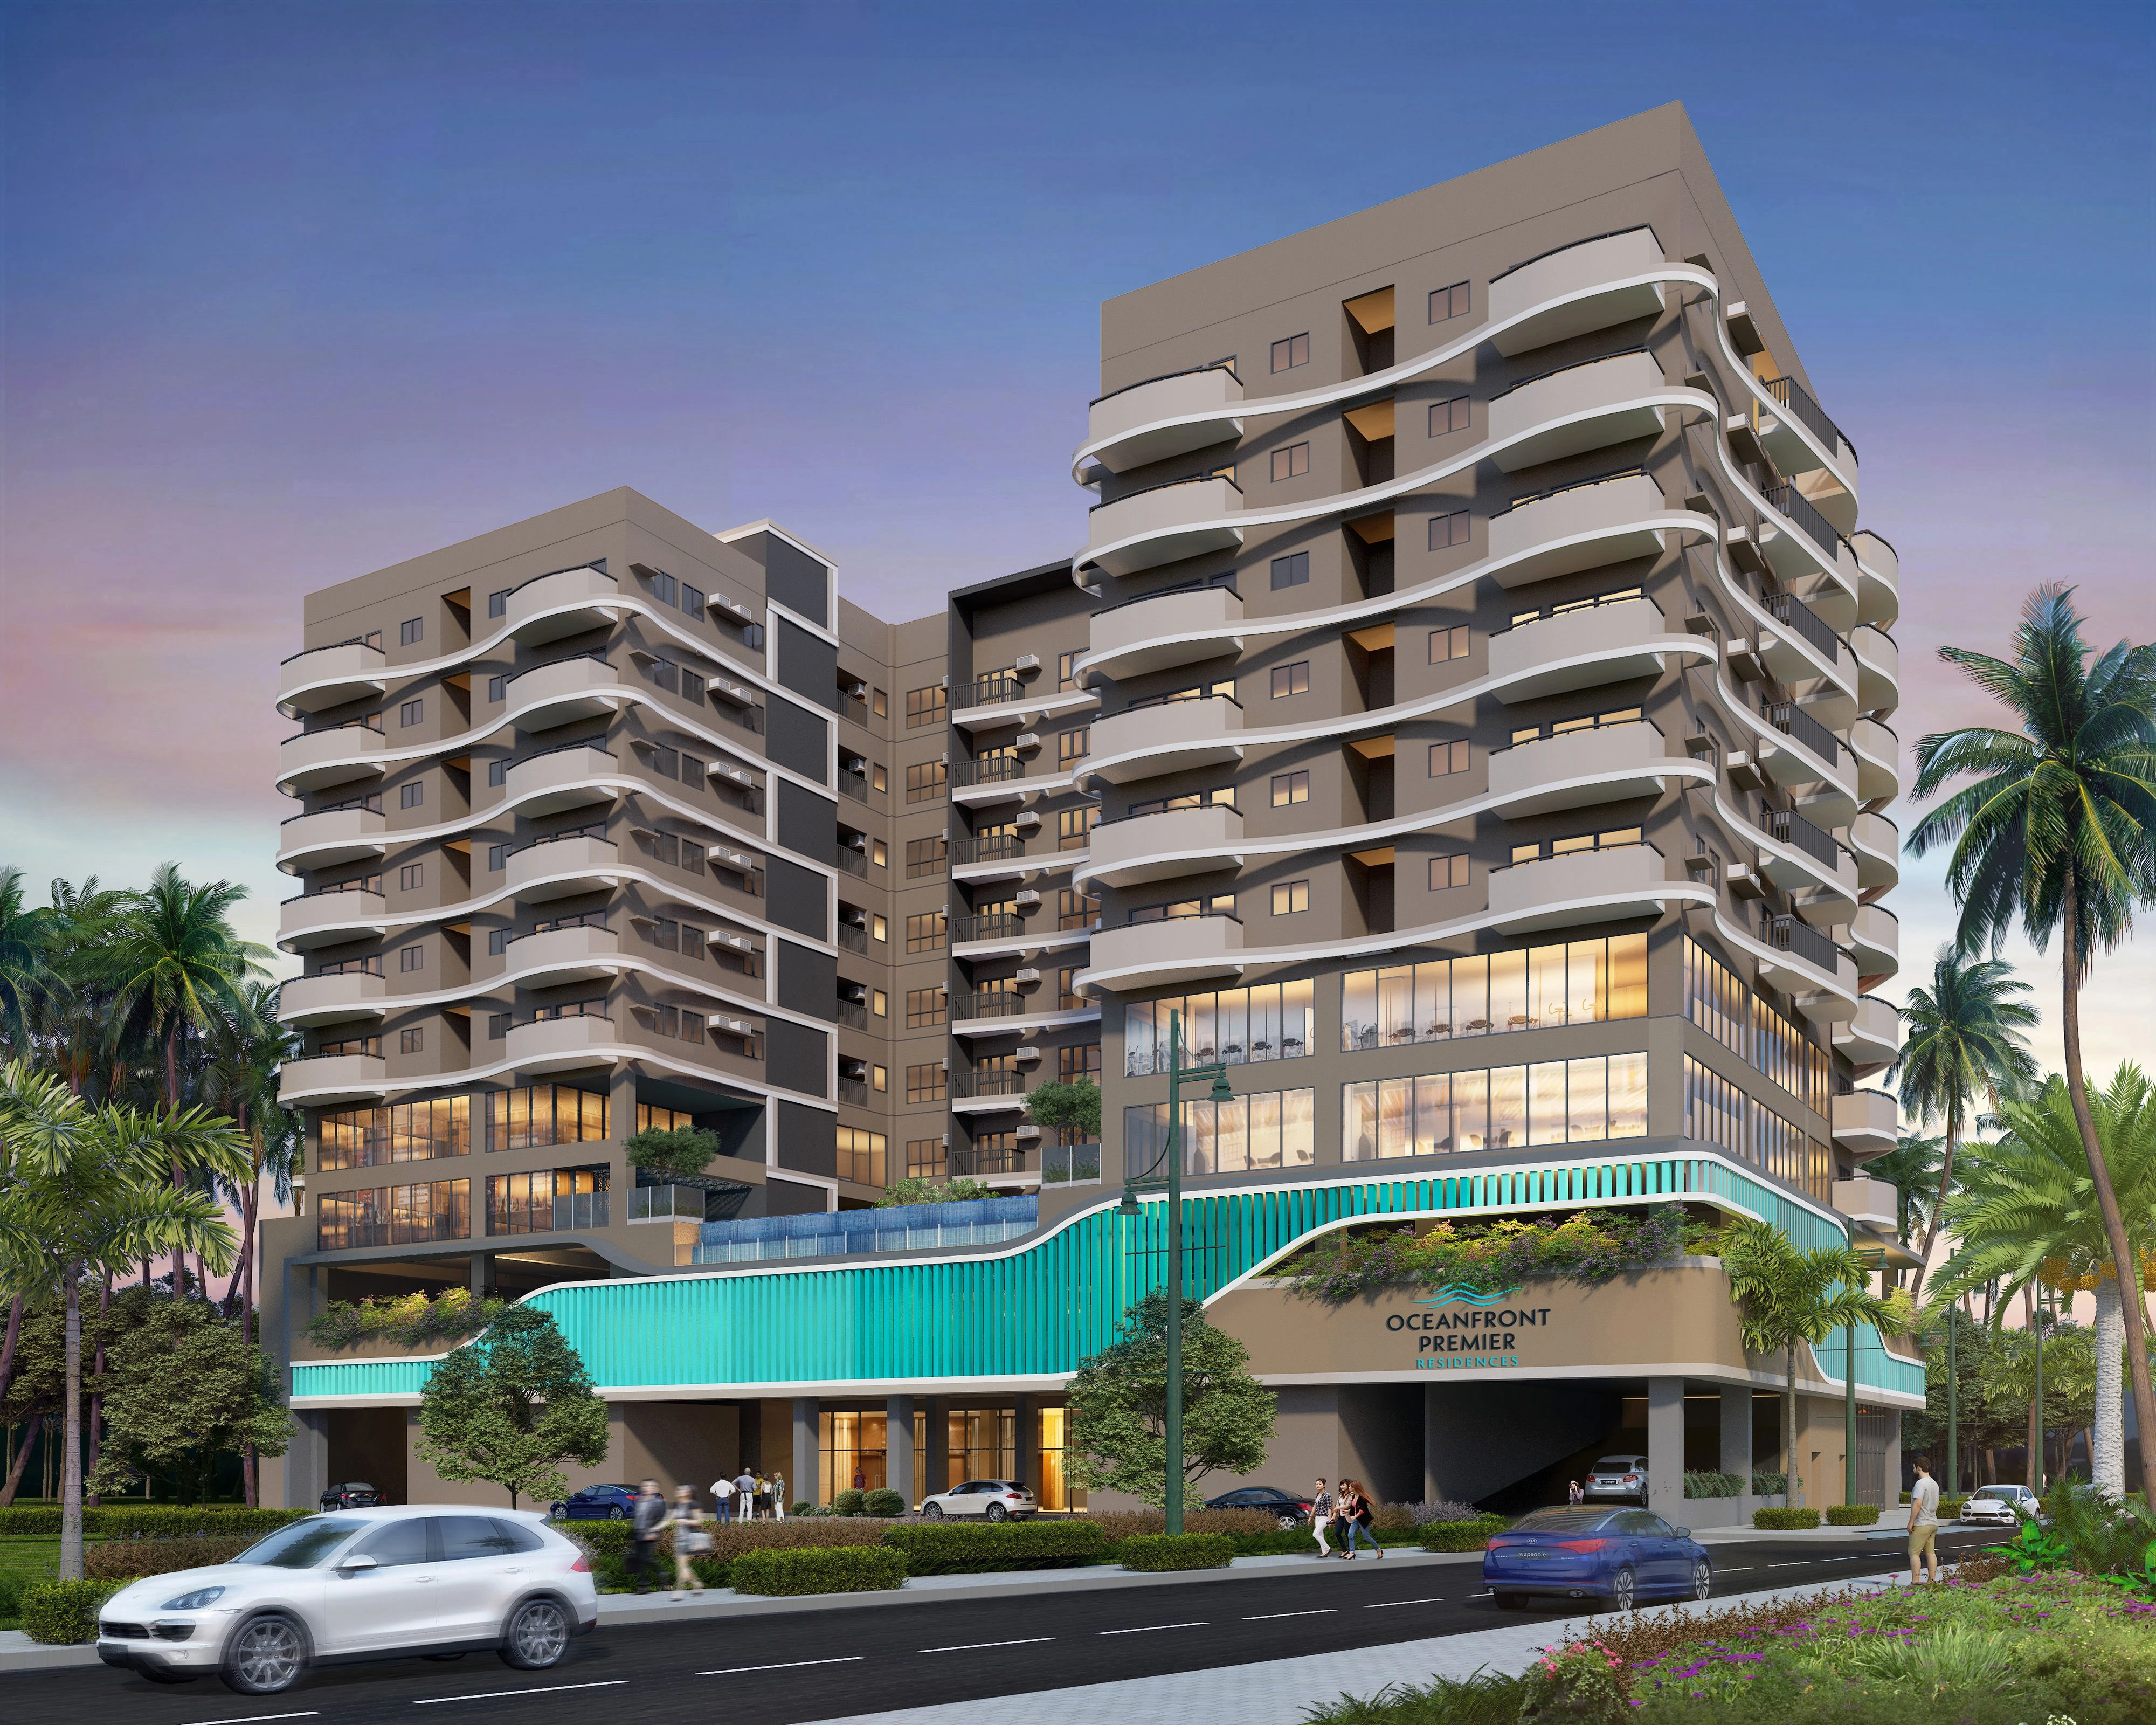 Developer projectOceanfront Premier ResidencesSan Vicente, PalawanPrice not publishedMegaworld
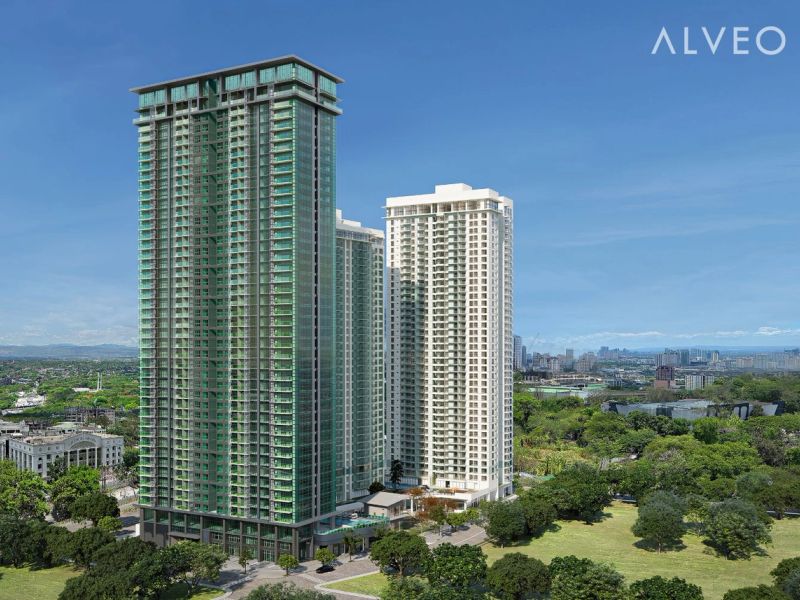 Developer projectOrean ResidencesTaguig, Metro ManilaPrice not publishedAyala Land
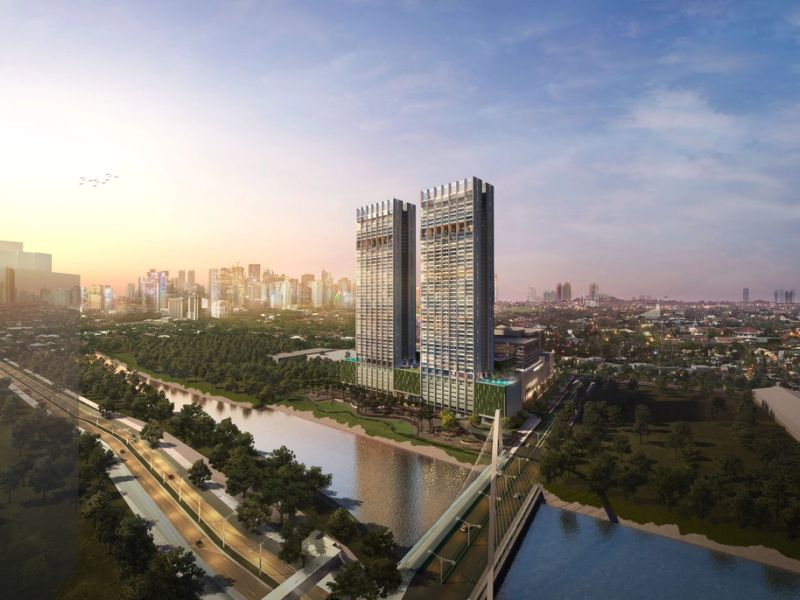 Developer projectParklinks North and South TowersQuezon CityPrice not publishedAyala Land
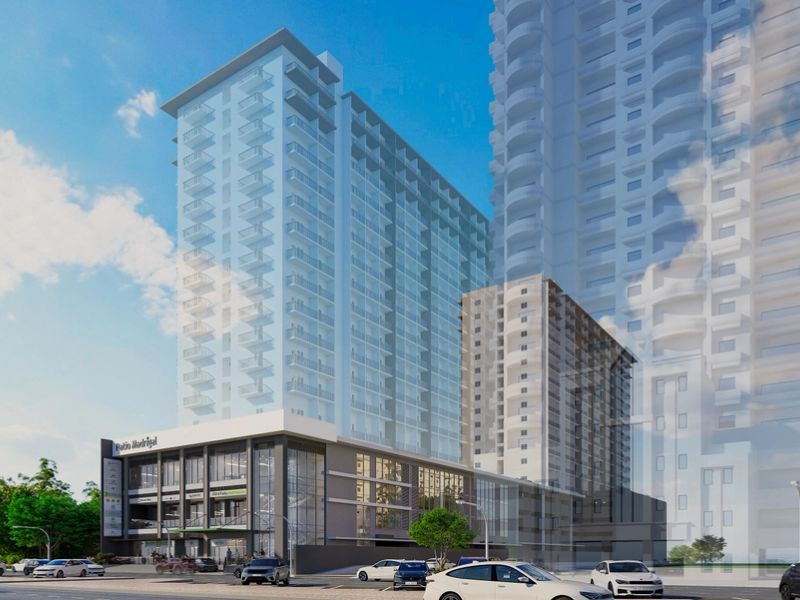 Developer projectPatio MadrigalParañaque, Metro ManilaPrice not publishedAyala Land
 Developer projectPatio Suites AbreezaDavao CityPrice not publishedAyala Land
 Developer projectSolara Park Storeys NuvaliNuvali, Santa Rosa, LagunaPrice not publishedAyala Land
 Developer projectThe LatticeTaguig, Metro ManilaPrice not publishedAyala Land
 Developer projectThe Residences at Azuela CoveDavao CityPrice not publishedAyala Land
What properties are you looking for?
How much is your budget?
Where is your preferred location?
Can't find what you want?
We have properties that aren't shown here. Tell us your budget and we'll search for you.
Sources: published housing-loan eligibility of major Philippine banks (BPI, BDO, Security Bank) as summarised by Nook and Expat Focus, 2026; Republic Act 4726 (Condominium Act); HighTech Mortgage licence disclosure (hightechmortgage.com). Lender programmes for foreign nationals are selective and change; terms are confirmed per application. Current as of October 2026.
Check your eligibility now
Can you get a loan for Philippine property? Check in one minute
Answer five questions and get the answer the lenders would give, before you spend anything. No rate quoted, no lender named; the real terms come from the bank for your file.
Questions buyers ask
Can a foreigner get a home loan in the Philippines?
Yes, for a condominium unit, through selected Philippine lenders that now accept foreign nationals, usually with 20% to 30% down, a shorter term, proof of income and often a long-term visa or Filipino co-borrower. Our broker arranges the loan.
Can a foreigner finance a house and lot?
No. Land financing is for Filipino citizens and dual citizens, because foreign nationals cannot hold title to land.
Does HighTech Mortgage lend on Philippine property?
No. HighTech Mortgage is a U.S. lender for U.S. borrowers and property. In a Philippine purchase it provides the U.S. escrow and digital-currency payment rail; the Philippine loan comes from a Philippine bank.
Can I combine developer financing with a bank loan?
Yes. Many buyers pay the down payment on the developer's pre-selling plan and take the bank loan at turnover; we match the turnover date to the lender's approval window.
Do Philippine banks check my U.S. credit score?
No. They do not pull foreign credit reports. They require a police or NBI clearance, no bankruptcy in the last two years, and proof of income; a few of these banks have offices in the United States.