
Rent-to-own in the Philippines is a lease with an option, or an obligation, to buy: you move in now, pay monthly, and part of each payment is credited toward the purchase price when you exercise the option. It suits buyers who are building the income history a bank wants to see, OFWs waiting to repatriate, and anyone who wants to live in a home before committing to it.
How a Philippine rent-to-own agreement works
- Option fee: an upfront amount, usually credited to the price if you buy and forfeited if you walk away.
- Monthly payment: rent plus a premium; the premium (or an agreed percentage) accumulates as your downpayment.
- Term and price lock: typically one to three years with the purchase price fixed at signing.
- Exercise: at the end of the term you pay the balance in cash or with bank financing, and title transfers.
Terms we negotiate for you
| Term | What protects the buyer |
|---|---|
| Credited share of rent | Stated as a fixed peso amount per month, not a vague percentage |
| Price | Fixed at signing, with the appraisal we obtain |
| Maintenance and dues | Who pays association dues, repairs and real property tax during the lease |
| Default and grace periods | Installment buyers of residential property have statutory grace periods and refund rights under the Maceda Law (Republic Act 6552); we structure the contract so those protections apply |
| Title check | Clean title, no liens, and the owner’s authority to sell before you pay the option fee |
Rent-to-own versus other creative deals
Rent-to-own is one of several structures we arrange: pasalo / assume-balance, subject-to purchases, workplace-housing packages for companies, and seasonal co-ownership. Each is matched to the buyer’s cash, timeline and financing position.
Rent-to-own homes and condos available now
44 individually available listing(s) matched. No source supplies unit-level availability, so the available-unit count is unknown rather than zero. We have properties that aren't shown here. Tell us your budget and we'll search for you. No. In-house financing is a purchase on installment from the developer. Rent-to-own is a lease with an option to buy, usually from a private owner; title transfers only when you exercise the option. An OFW or dual citizen can on any property. A foreign national can on a condominium unit within the project’s 40% foreign share; for a house and lot the eventual purchase must use a lease, corporation or Filipino-spouse structure. Typically the option fee and the credited premium are forfeited, while the rent portion is simply rent. We negotiate the refund terms up front so you know the cost of walking away. Yes. Many buyers use the rent-to-own period to build the income history a Philippine bank will require; our broker arranges the take-out loan when the term ends.Available properties
 ListingVacant Lot for Sale at Club Morocco Residential Estates, SubicSubic Bay, Zambales, SubicPHP 1,200,0002 bed · 171 m²
 ListingVacant Lot for Sale at Club Morocco Residential Estates, SubicSubic Bay, Zambales, SubicPHP 1,200,0002 bed · 171 m²
 ListingVACANT LOT – Club Morocco, Subic ZambalesParanaque, SubicPHP 1,200,000171 m²
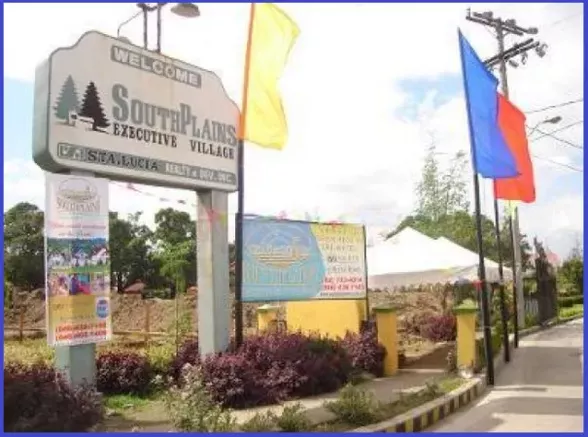 ListingResidential lot in South Plains Executive Village, Dasmarinas, CaviteDasmarinas, Cavite, DasmarinasPHP 1,776,0003 bed · 152 m²
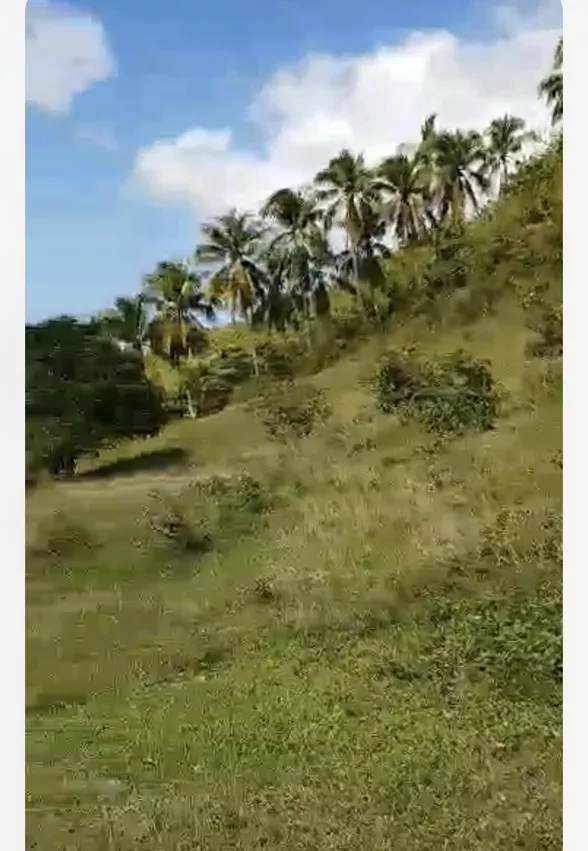 Listing1.3-Hectare Lot in Tuburan, Cebu — Near Colonia Elementary SchoolTuburan, Cebu, Tuburan CebuPHP 2,650,000
 ListingHouse and Lot for Sale in Teresa, RizalTeresa, Rizal, TeresaPHP 3,000,0002 bed · 2 bath · 51 m²
 ListingAyala Condo studio fully furnished for sale in MuntinlupaMetro Manila, AlabangPHP 3,000,0001 bed · 1 bath · 22.4 m²
 Listing24.95 sqm Office Unit for Sale — Cityland Herrera Tower, MakatiMakati, Metro Manila, MakatiPHP 3,200,00025 m²
 Listing19.5 sqm Studio Condo for Sale — RLC Gateway Regency, Mandaluyong (Move-In Ready)Metro Manila, MandaluyongPHP 3,800,0001 bed · 1 bath · 19.5 m²
 ListingBerkley Residences Condominium Unit For Sale Katipunan/QCQuezon City (QC), Metro Manila, Quezon CityPHP 3,900,0001 bed · 2 bath · 24.4 m²
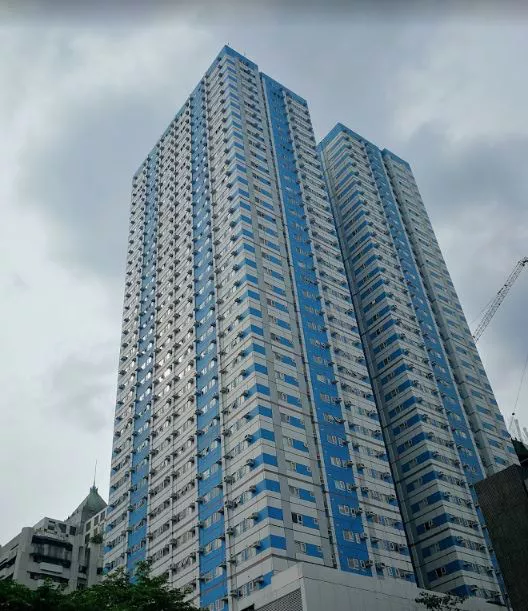 Listing24 sqm Studio Condo at The Pearl Place, Pasig — Near University of Asia & the PacificPasig, Metro Manila, PasigPHP 4,440,0001 bed · 1 bath · 24 m²
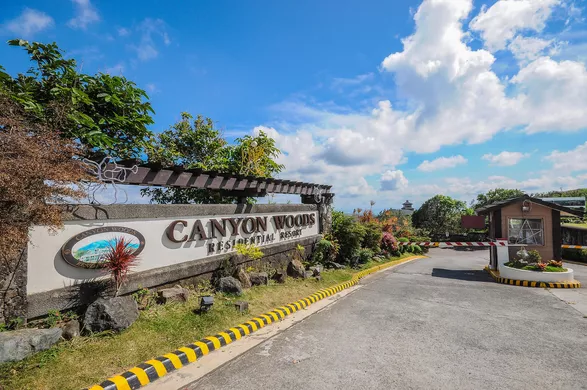 ListingResidential Lot for Sale at Canyon Woods Resort — Laurel, Batangas (near Tagaytay)Tagaytay, Batangas, LaurelPHP 4,710,0002 bed · 305 m²
 ListingCondo for Sale at Solemare Parksuites, ParañaqueParanaque, Metro Manila, ParanaquePHP 4,950,0001 bed · 1 bath · 28 m²
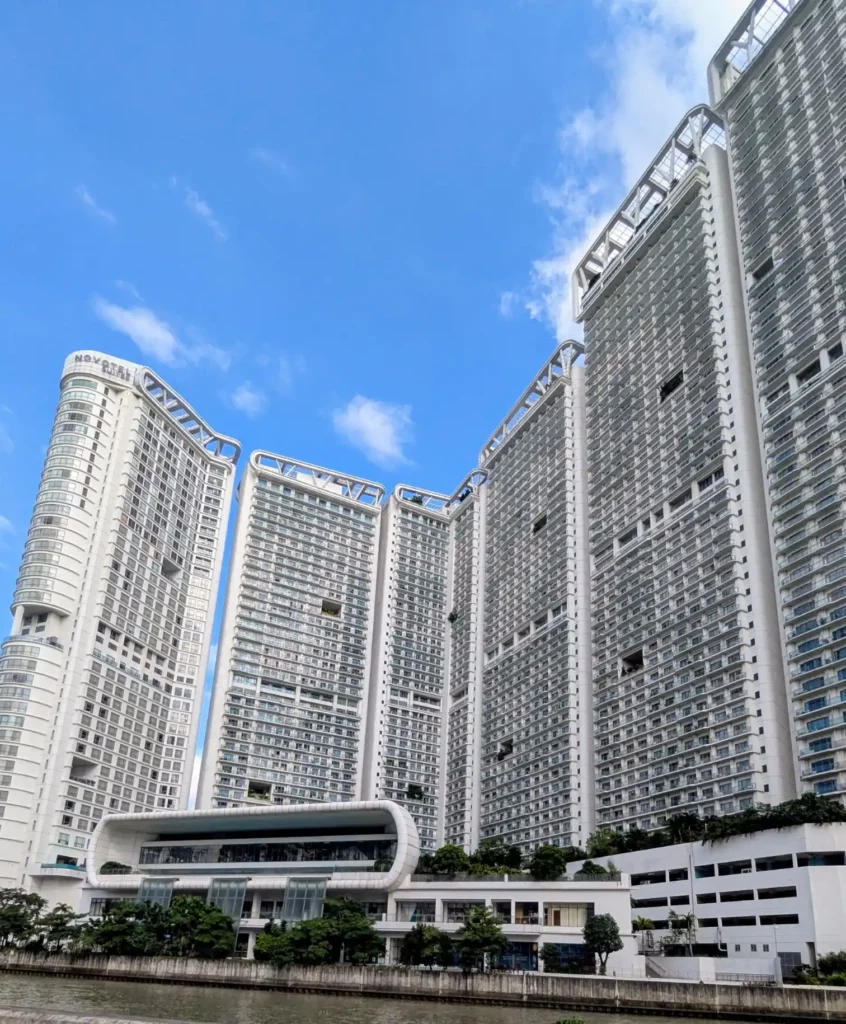 ListingAcqua-Skyline & River View Condo – MandaluyongMandaluyong, Metro ManilaPHP 5,000,0001 bed · 1 bath · 24.8 m²
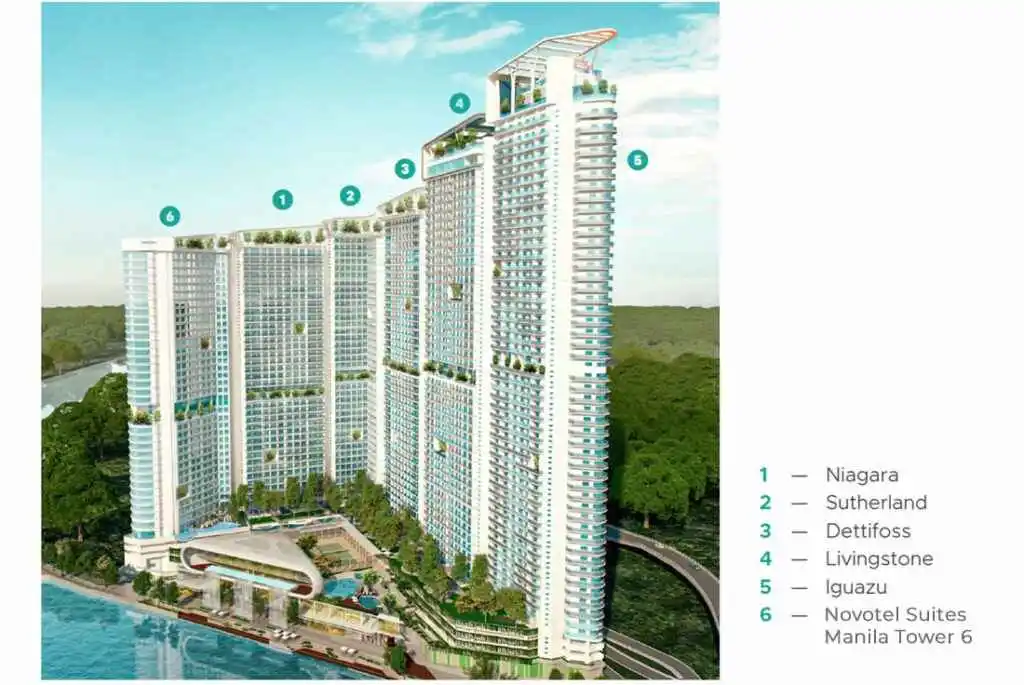 ListingAqua Residences Penthouse Condo for Sale — 1 Bedroom, Mandaluyong (Move-In Ready)Mandaluyong, Metro ManilaPHP 5,000,0001 bed · 1 bath · 24.8 m²
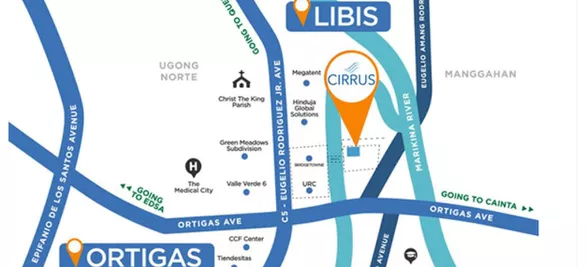 ListingStudio Condo Cirrus Bridgetowne East RLC, Pasig 24smNasugbu, Metro Manila, PasigPHP 5,500,0001 bath · 24 m²
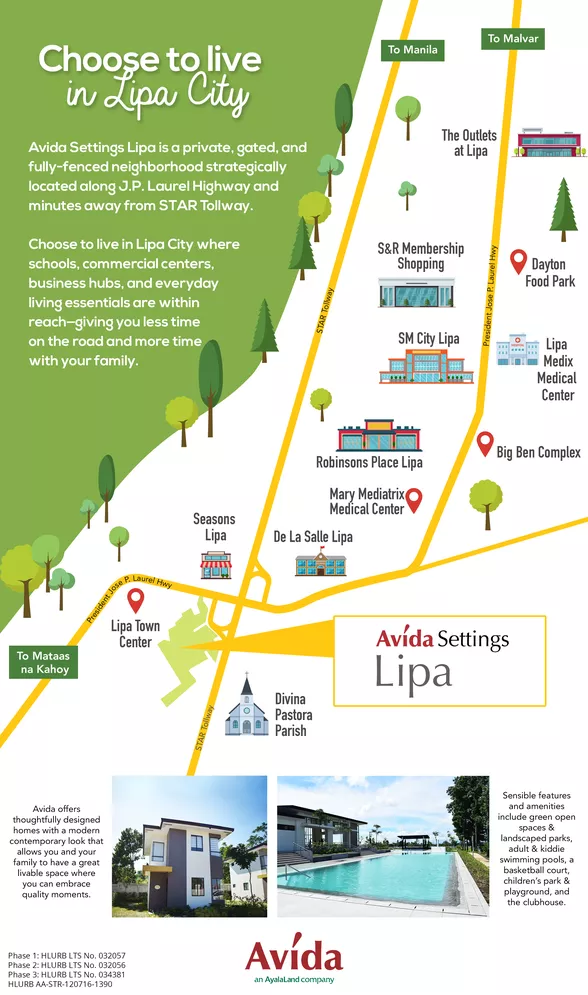 ListingAffordable Residential Lot for sale by Ayala Avida in Lipa BatangasTagaytay, Batangas, LipaPHP 6,400,0001 bed · 143 m²
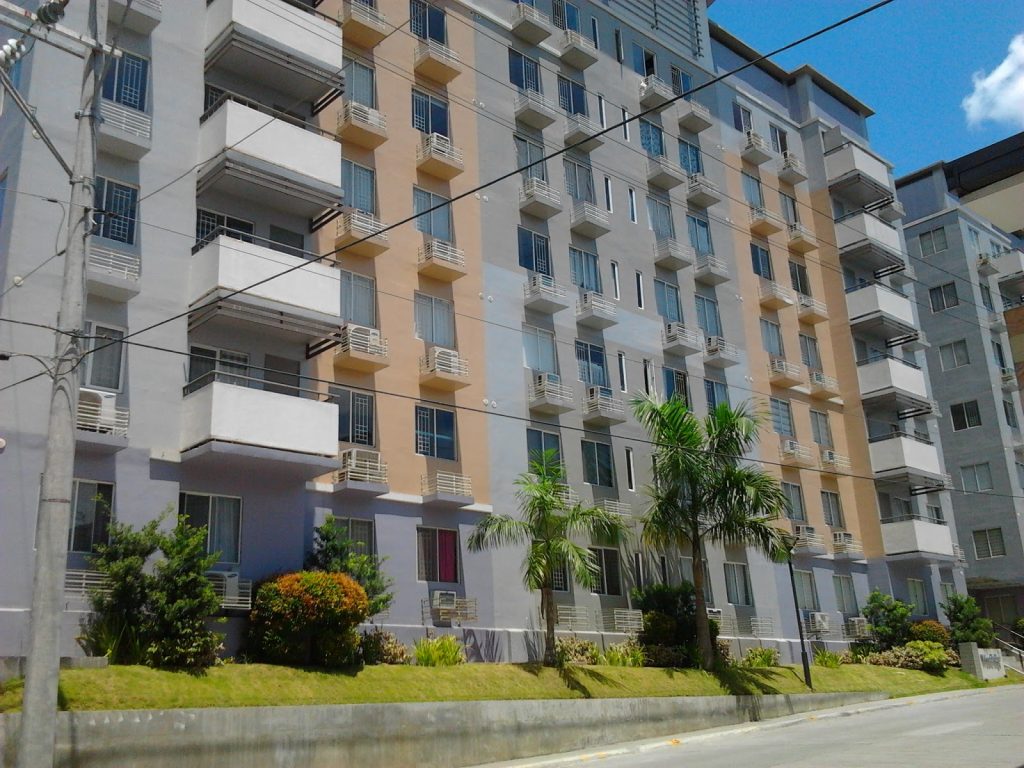 Listing2-Bedroom Condo with Parking for Sale — Sofia Bellevue, Quezon City (Ground Floor)Quezon City (QC), Metro Manila, Quezon CityPHP 7,000,0002 bed · 1 bath · 36 m²
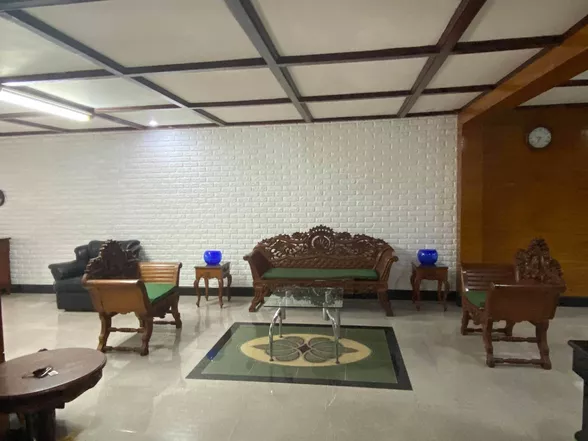 ListingHouse and Lot for Sale in Tuy, BatangasTuy, Batangas, TuyPHP 9,000,0003 bed · 4 bath · 333 m²
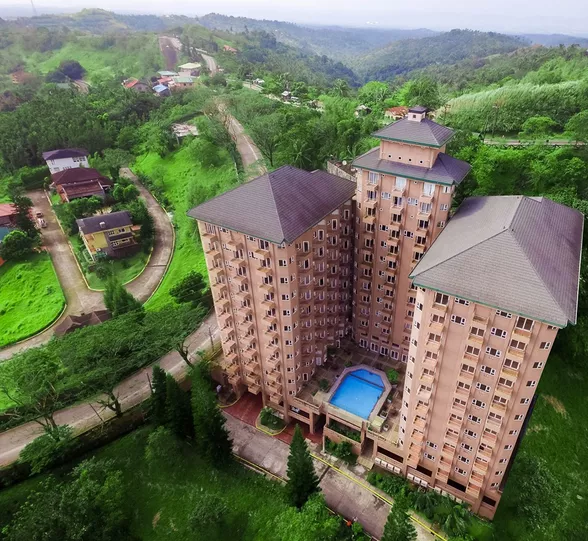 ListingCANYON Woods Residential Lot, Laurel, BatangasTuy, Batangas, LaurelPHP 9,000,0003 bed · 4 bath · 333 m²
 Listing1-Bedroom Condo for Sale — Avida Serin West Tower 2, TagaytayTagaytay, Cavite, TagaytayPHP 9,000,0001 bed · 2 bath · 41 m²
 ListingAyala Amaia Series Vermosa Townhouse for Sale — Assumable Mortgage, Imus CaviteImus, Cavite, ImusPHP 12,100,0003 bed · 2 bath · 60 m²
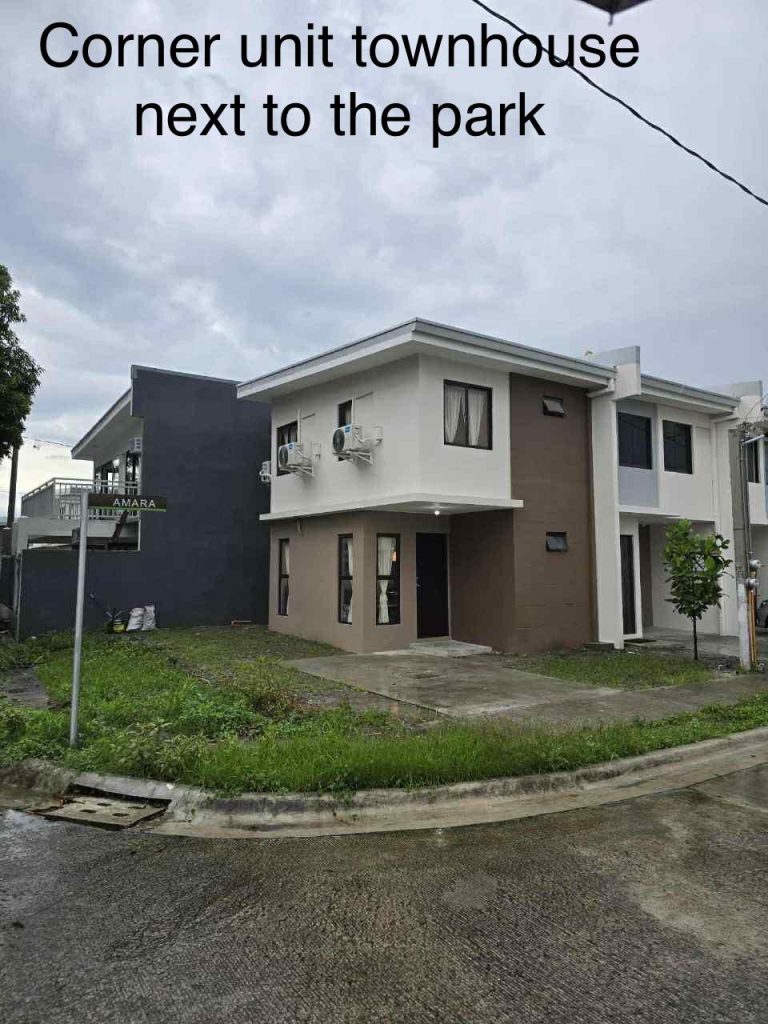 ListingAyala Amaia Series Vermosa #Pasalo #RUSH SALE, Imus, CaviteImus, CavitePHP 12,100,0002 bath · 60 m²
What properties are you looking for?
How much is your budget?
Where is your preferred location?
Can't find what you want?
Questions buyers ask
Is rent-to-own the same as in-house financing?
Can an OFW or a foreigner do rent-to-own?
What happens to my payments if I decide not to buy?
Can I switch to a bank loan at the end of the term?